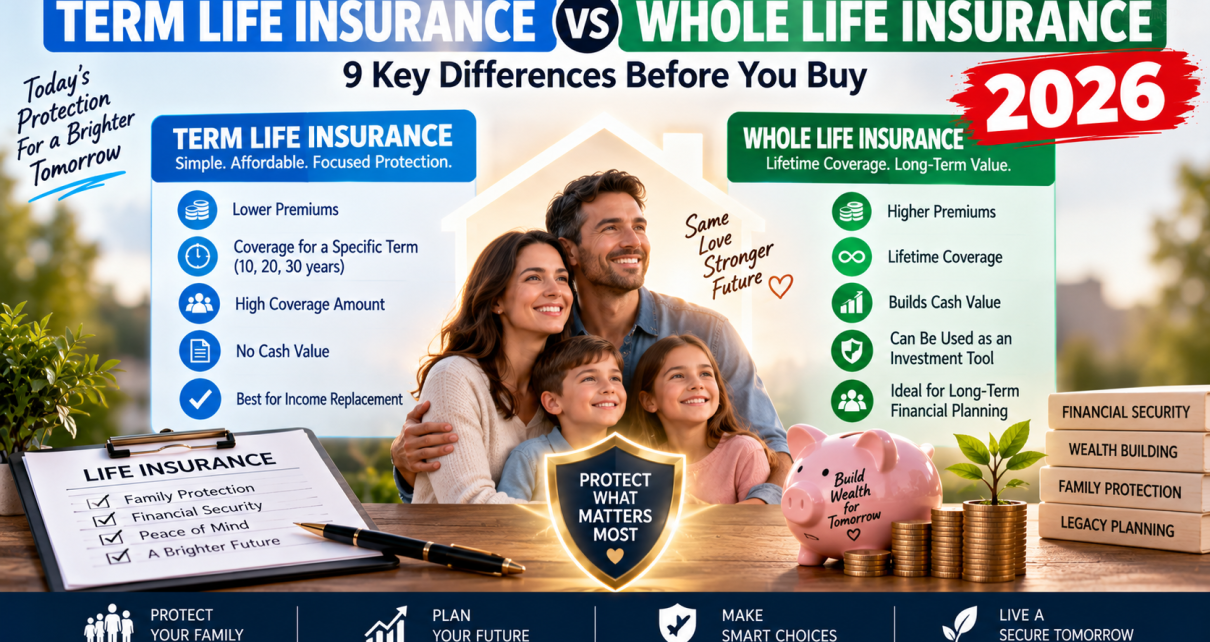
Term Life Insurance vs Whole Life Insurance 2026: 9 Key Differences Before You Buy
Life insurance is designed to provide financial protection for the people who depend on you, but choosing the right type of policy can be confusing. Two of the most commonly discussed options are term life insurance and whole life insurance.
Although both can provide a death benefit to your beneficiaries, they work in very different ways.
Term life insurance provides coverage for a specific period, such as 10, 15, 20, or 25 years. Whole life insurance is designed to provide lifelong coverage and also includes a cash value component that can build over time.
The difference is not simply about price. The two products can serve different financial needs, have different levels of complexity, and provide different features while you are alive.
Before buying a policy in 2026, it is important to understand what you are actually paying for, how long your coverage can last, what happens when a term ends, and whether the policy provides features beyond the death benefit.
Here are nine key differences between term life insurance and whole life insurance that you should understand before making a decision.
- Temporary Coverage vs. Lifelong Coverage
The most fundamental difference between term life insurance and whole life insurance is how long the coverage is designed to last.
Term life insurance is temporary coverage.
When you purchase a term policy, you select a specific coverage period. Depending on the policy, that might be 10, 15, 20, or another specified number of years.
For example, imagine someone purchases a 20-year term life insurance policy with a $500,000 death benefit. During the covered term, the policy is designed to provide that $500,000 death benefit if the insured person dies while the policy is active and the policy conditions are satisfied.
Once the term ends, the original term coverage does not simply continue indefinitely under the same terms.
This is where the idea of term insurance being “rented” coverage comes from. You are paying for protection during a defined period rather than purchasing a policy designed to remain in force for your entire life.
Whole life insurance works differently.
Whole life insurance is designed to provide coverage for the insured’s entire life, subject to the policy’s terms and continued compliance with those terms. This means the policy is not built around a 10-, 20-, or 30-year coverage period in the same way term insurance is.
For someone whose primary objective is to have life insurance available throughout their lifetime, this distinction can be particularly important.
The key question is therefore not simply which product is cheaper. It is how long you want or need the coverage to remain in place.
- Premium Cost
Price is one of the biggest differences between term and whole life insurance.
Term life insurance is generally less expensive because the insurer is providing coverage for a limited period rather than designing the policy around lifelong coverage.
For someone primarily looking for a death benefit during a specific stage of life, this can make term insurance an attractive option.
For example, a person may want coverage while they have a mortgage, dependent children, or other major financial responsibilities. During that period, the death benefit can be intended to help protect the household if the insured dies.
Whole life insurance generally costs more.
The higher premium reflects the broader structure of the policy, including its lifelong coverage and cash value component.
This creates an important distinction when comparing policies.
With term insurance, a larger portion of the discussion tends to center around obtaining a specific amount of protection for a defined period.
With whole life insurance, the premium is supporting a policy that is designed to remain in force for life and includes additional features.
Because of this, comparing the two policies purely by monthly premium can be misleading.
A lower premium does not necessarily mean the policy provides the same features. Conversely, paying more for whole life insurance does not automatically mean it is appropriate for every person.
The product needs to match the financial purpose behind the insurance.
- What Happens When the Term Ends?
One of the most important considerations with term life insurance is what happens when the coverage period expires.
Suppose you purchase a 25-year term policy at age 25. At age 50, the original 25-year term has ended.
At that point, you need to understand the specific policy provisions governing renewal, conversion, or expiration.
The source material emphasizes an important issue: obtaining new coverage later in life can become more expensive because age is one of the factors that can affect insurance costs and insurability.
The older you are when applying for new coverage, the circumstances surrounding that application may be different from when you originally purchased your policy.
Health and other underwriting factors can also matter.
This creates a potential challenge for someone who assumes that inexpensive term insurance purchased at a young age will automatically provide the same protection decades later.
The initial affordability of term insurance is therefore only part of the equation.
You should also understand what happens at the end of the selected term before purchasing the policy.
Some policies may include renewal provisions, while others may provide conversion opportunities. The exact rules depend on the policy and insurer.
This is why reading the policy terms is important rather than assuming that every term insurance policy works in exactly the same way.
- Cash Value: A Major Difference Between the Two
Another major difference is the cash value component.
Traditional term life insurance primarily provides a death benefit during the policy’s covered period. It does not operate in the same way as a whole life policy with a cash value component.
Whole life insurance, on the other hand, includes cash value as part of its structure.
The cash value can grow according to the terms of the policy, creating a value associated with the policy while the insured is alive.
This is one of the features that makes whole life insurance more complex than term insurance.
The source describes cash value as something that can potentially be accessed through borrowing or other policy mechanisms. The people in the source explain how they have used loans against a whole life policy for other financial purposes.
However, cash value should not simply be treated as free money.
Using cash value or borrowing against a policy can have consequences depending on the policy structure, interest, outstanding loan balance, and other provisions.
Anyone considering whole life insurance should understand how cash value works under the specific policy being offered rather than assuming that every whole life policy has identical results.
The key difference remains straightforward:
Term insurance primarily focuses on temporary life insurance protection.
Whole life insurance combines lifelong life insurance coverage with a cash value component.
That additional structure is one reason whole life insurance can require more explanation before purchase.
- Death Benefit Structure
The death benefit is another area where the source distinguishes the two products.
With term insurance, the death benefit is generally established when the policy is purchased and remains associated with the policy during the selected term, subject to its terms.
For example, a $500,000 term policy is intended to provide a $500,000 death benefit during the covered period if the policy conditions are met.
If your financial responsibilities increase substantially later, the original policy does not automatically become a larger policy simply because your income or assets have increased.
You may need additional coverage to address those additional responsibilities.
This can become important as your financial situation changes.
Imagine that someone buys $500,000 of coverage when they are younger. Years later, they have a larger mortgage, additional assets, children approaching college age, and a significantly higher household income.
The original $500,000 policy may no longer represent the amount of financial protection they want.
That person may need to review their coverage and potentially obtain additional insurance.
Whole life insurance has a different structure.
The source explains that whole life policies can have a death benefit that increases over time under the policy structure.
The exact mechanics vary between policies, so prospective buyers should examine the policy illustration and guaranteed versus non-guaranteed elements carefully.
The broader lesson is that your life insurance needs should not necessarily be considered permanent just because you purchased a policy years ago.
Your income, debts, assets, family responsibilities, and long-term financial goals can change.
Regularly reviewing your coverage can therefore be important regardless of whether you own term or whole life insurance.
- Living Benefits and Access While You Are Alive
Life insurance is primarily associated with the death benefit paid to beneficiaries, but whole life insurance can provide additional features while the insured is alive.
The source places significant emphasis on the ability to access the policy’s cash value.
Depending on the policy structure, a policyholder may be able to borrow against the cash value and use the funds for other purposes.
This is one of the features that distinguishes whole life insurance from straightforward term coverage.
However, it is important to understand the difference between having access to a financial feature and receiving a guaranteed financial benefit.
Policy loans can involve interest and can affect the policy’s value and death benefit depending on how they are handled.
Therefore, anyone considering this strategy should understand the specific policy rules and potential consequences before using the cash value.
Whole life insurance can also include additional living benefits or riders depending on the insurer and policy.
These features can provide additional functionality beyond the basic death benefit.
Term life insurance is generally simpler.
Its primary purpose is to provide a death benefit during the selected coverage period.
This simplicity can itself be valuable for people who want straightforward protection without a more complicated policy structure.
- Complexity and Financial Management
Term life insurance is generally easier to understand.
You select an amount of coverage, choose a term, pay the required premiums, and maintain the policy according to its conditions.
The simplicity can make it easier for someone to understand what they are purchasing.
Whole life insurance requires more attention.
Because it can include lifelong coverage, cash value, policy loans, potential riders, and other features, there are more moving parts to understand.
This does not necessarily make whole life insurance unsuitable.
It simply means the buyer needs to understand the policy beyond its headline death benefit.
For example, if a policy includes a cash value component, you should understand how that value is calculated, what is guaranteed, what is not guaranteed, how loans work, what interest may apply, and what happens to the policy under different scenarios.
A good insurance decision should therefore involve more than asking how much the monthly premium is.
You should understand what the premium buys and what responsibilities come with maintaining the policy.
This is especially important for long-term financial products because a policy can remain in place for many years.
- Term Conversion Can Create Another Path
Another important concept discussed in the source is conversion.
Some term life insurance policies include a conversion provision that allows the policyholder to convert eligible term coverage into a permanent life insurance policy, subject to the policy’s rules.
This can provide a useful middle ground for people who want affordable temporary coverage when they are younger but may later want permanent coverage.
For example, someone could purchase term insurance when they have a limited budget and significant financial responsibilities.
Later, if their financial situation changes or they decide that lifelong coverage is important, they may have an opportunity to convert some or all of their eligible term coverage into a permanent policy, depending on the specific contract.
The source emphasizes that the availability of conversion depends on the insurer and the products it offers. Not every term policy can automatically be converted into every type of permanent policy.
Therefore, if conversion is important to you, it should be one of the questions you ask before purchasing the term policy.
Find out:
Whether the policy is convertible.
When the conversion option expires.
Which permanent policies are available for conversion.
Whether additional underwriting is required.
Whether there are limits on the amount that can be converted.
What happens to your premium after conversion.
These details can significantly affect the usefulness of the conversion feature.
- Matching the Policy to Your Financial Goals
The final and perhaps most important difference is the purpose each type of insurance can serve within a broader financial plan.
Term life insurance can be used when the primary objective is affordable protection for a defined period.
For example, a household may want coverage while children are dependent, while a mortgage remains outstanding, or while the family relies heavily on the insured person’s income.
The source emphasizes that calculating coverage should involve more than simply asking whether a mortgage can be paid off.
A household may have many other financial responsibilities, including education costs, ongoing living expenses, debt, and the economic value of the insured person’s income.
This means a policy should be evaluated based on the financial needs it is intended to address.
Whole life insurance can serve a different role.
Its lifelong coverage and cash value component can make it relevant to people who want permanent insurance and are comfortable paying higher premiums for additional policy features.
The source also discusses using whole life insurance as part of a broader strategy involving savings, liquidity, and access to policy cash value.
However, the suitability of such a strategy depends on the individual’s circumstances and the specific policy.
The important point is that life insurance should not be purchased simply because one type is described as universally better.
Your financial objective should come first.
Term Life Insurance vs Whole Life Insurance: Side-by-Side Comparison
Term Life Insurance
Coverage duration:
Temporary, based on the selected policy term.
Premium:
Generally lower than whole life insurance for comparable death benefit amounts.
Cash value:
The source contrasts term insurance with whole life by noting that term does not have the same cash value component.
Primary purpose:
Life insurance protection during a defined period.
Complexity:
Generally simpler.
Renewal:
Coverage arrangements need to be reviewed when the term ends, based on the policy’s provisions.
Conversion:
Some policies may offer conversion to permanent coverage.
Best understood as:
A straightforward way to obtain life insurance protection for a specific period.
Whole Life Insurance
Coverage duration:
Designed to provide lifelong coverage, subject to policy terms.
Premium:
Generally higher than term insurance.
Cash value:
Includes a cash value component.
Primary purpose:
Lifelong protection combined with additional policy features.
Complexity:
Generally more complex because of the cash value and other policy provisions.
Access during life:
Cash value may provide access to funds through mechanisms such as policy loans, subject to the policy’s terms.
Best understood as:
A permanent life insurance product with additional financial features.
How Much Life Insurance Coverage Do You Actually Need?
One of the most important lessons from the source is that life insurance should not be based solely on one financial obligation.
For example, paying off the mortgage may be an important goal, but it may not be enough to replace the financial contribution of the person who dies.
Consider the broader picture.
A household may need to account for:
Mortgage or housing costs
Outstanding debts
Childcare
Education expenses
Daily living costs
Future financial obligations
Loss of income
Existing assets
Savings
Other insurance coverage
The financial needs of dependents
The purpose of this exercise is not necessarily to produce a perfect number. Instead, it helps you understand the financial gap your life insurance is supposed to address.
The source specifically encourages considering expenses beyond the mortgage, including education and future household costs.
This is particularly important when the insured person is a major income earner.
A death benefit can provide financial resources to beneficiaries, but the amount should be considered in relation to the financial responsibilities it is intended to address.
Why Buying Life Insurance Young Can Matter
Age can be an important consideration when purchasing life insurance.
The source discusses the idea of obtaining coverage while you are younger, when insurance can generally be less expensive than obtaining comparable coverage later in life.
Term insurance can therefore be used to obtain a larger death benefit at a relatively lower premium during a period when financial responsibilities may already be significant.
For example, a younger parent may have children, a mortgage, and many years of income that the household expects to rely upon.
Purchasing coverage early can address those risks during an important period.
However, purchasing insurance young does not mean you should automatically choose one type of policy.
The appropriate policy still depends on the purpose of the coverage, budget, desired duration, and features you need.
Should You Buy Term and Whole Life Insurance Together?
The source also describes a strategy involving both types of insurance.
Rather than viewing term and whole life insurance as mutually exclusive, some people use both products for different purposes.
For example, term insurance can provide a larger amount of temporary coverage at a lower premium, while whole life insurance can provide permanent coverage and cash value features.
This approach can potentially allow someone to address different financial needs with different insurance products.
However, combining policies also means paying for multiple forms of coverage and understanding how each policy works.
The strategy should therefore be based on specific financial goals rather than simply purchasing more insurance.
A person with a limited budget may prioritize affordable term coverage.
Someone with a different financial situation may have reasons to consider permanent coverage as part of a broader financial strategy.
The key is to understand why each policy exists within the overall plan.
Common Mistakes to Avoid Before Buying Life Insurance
One common mistake is focusing only on the monthly premium.
A cheaper policy can look attractive, but if it expires before the period when coverage is needed, the policy may not accomplish the intended goal.
Another mistake is buying too little coverage.
If your financial responsibilities are substantial, simply covering one debt may not be enough to protect your household from the loss of your income.
A third mistake is failing to understand what happens when a term policy ends.
Before purchasing term insurance, understand the expiration, renewal, and conversion provisions.
A fourth mistake is assuming that all whole life policies work in exactly the same way.
Policy features, cash value mechanics, premiums, guarantees, riders, and loan provisions can vary.
You should review the actual policy documents and illustration rather than relying solely on a general description of whole life insurance.
Finally, do not confuse life insurance with a universal investment product.
Whole life insurance has financial features beyond the death benefit, but it remains a life insurance product. Any cash value or borrowing strategy should be evaluated based on the actual policy terms and your broader financial circumstances.
Questions to Ask Before Buying a Policy
Before purchasing either term or whole life insurance, consider asking the insurer or licensed professional the following questions:
How long will the coverage remain in force?
What exactly is the death benefit?
How much will the premium be?
Is the premium guaranteed?
What happens when the term ends?
Can the policy be renewed?
Can the policy be converted?
What permanent policies are available for conversion?
Does the policy have cash value?
How does the cash value grow?
Which values are guaranteed?
How do policy loans work?
What interest is charged on policy loans?
How can loans affect the death benefit?
What riders or living benefits are available?
What happens if I stop paying premiums?
These questions can help you understand the actual contract rather than making a decision based only on a sales summary.
Final Thoughts
Term life insurance and whole life insurance can both provide valuable financial protection, but they are structured for different purposes.
Term life insurance is temporary coverage designed for a defined period. Its major advantages are simplicity and generally lower premiums. It can be useful when you want to protect your household during years when financial responsibilities are particularly high.
Whole life insurance is designed to provide lifelong coverage and includes a cash value component. It generally costs more and is more complex, but it can provide features that term insurance does not offer.
The most important question is not simply whether term or whole life insurance is “better.”
The more useful question is: What financial problem are you trying to solve?
If your primary need is affordable protection for a specific period, term insurance may fit that objective.
If you want permanent coverage and are specifically interested in the additional features associated with whole life insurance, a whole life policy may be worth evaluating.
In some financial strategies, people may also use both types of coverage for different purposes.
Whatever option you consider, calculate your actual financial needs, understand the policy’s terms, compare costs, and pay close attention to what happens when coverage changes or ends.
Life insurance is ultimately about protecting the people and financial responsibilities that matter to you. The right policy is the one whose structure, cost, duration, and features align with the specific protection you are trying to create.
