Home Equity Loan vs HELOC 2026: 9 Key Differences You Should Know Before Borrowing
If you own a home and have built up significant equity, you may have access to a valuable source of borrowing power. But turning that equity into usable cash is not as simple as choosing any loan available.
Two of the most common options are a home equity loan and a home equity line of credit, commonly called a HELOC.
Both allow homeowners to borrow against the equity they have built in their homes. However, they work very differently.
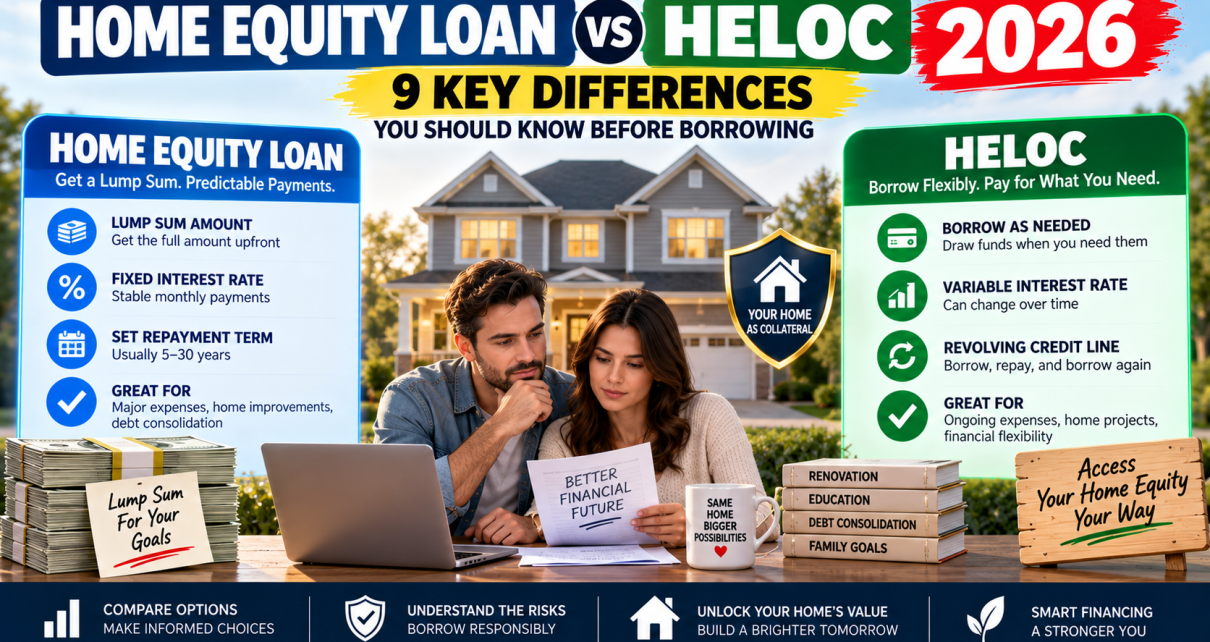
A home equity loan generally provides a lump sum of money, while a HELOC works more like a revolving line of credit that allows you to borrow money as needed during a specific draw period.
That difference can affect your interest costs, monthly payments, flexibility, and the amount of risk you take on.
Before borrowing against your home in 2026, it is important to understand exactly how these products work and when each one may make sense.
Here are nine key differences between a home equity loan and a HELOC that you should know before borrowing.
- Lump Sum vs. Line of Credit
The most fundamental difference between a home equity loan and a HELOC is how you receive the money.
A home equity loan generally provides a lump sum.
For example, suppose you need $50,000 for a major project. With a home equity loan, you may borrow the $50,000 upfront and then repay the loan according to its terms.
This makes the structure relatively straightforward.
You know the amount you are borrowing at the beginning, and the loan is structured around that amount.
A HELOC works differently.
A home equity line of credit is a revolving line of credit secured by your home. Instead of receiving the entire amount at once, you have access to a credit line and can generally draw money as you need it during the draw period.
The source compares this structure to a credit card, although a HELOC is designed for much larger financial needs and uses your home as collateral.
For example, imagine you have a $75,000 HELOC.
You might use $15,000 initially for a home improvement project and later access additional funds if you need them, assuming you remain within the available credit limit and comply with the lender’s terms.
This flexibility is one of the biggest differences between the two products.
A home equity loan is generally designed around one specific borrowing event.
A HELOC can provide access to money over time.
- Fixed Rate vs. Variable Rate
Interest rate structure is another major difference to understand.
Home equity loans are commonly structured with a fixed interest rate, although the exact terms depend on the lender and product.
A fixed rate means the interest rate does not fluctuate with market conditions during the applicable period of the loan.
A HELOC, on the other hand, often uses a variable interest rate.
The source explains that variable HELOC rates are typically tied to the prime rate, with the lender applying a specific adjustment or margin to determine the rate charged to the borrower.
This means the interest rate on a HELOC can change over time.
If the underlying rate rises, the interest rate on the HELOC may rise as well. If rates move in the opposite direction, the borrowing cost may change accordingly.
Some lenders offer fixed-rate HELOC options, but these are not universally available and can involve a higher rate than a variable-rate HELOC.
This creates a trade-off.
A variable-rate HELOC may initially offer a more attractive rate but exposes the borrower to potential changes in borrowing costs.
A fixed-rate option can provide more predictability, but the initial rate may be higher.
Before choosing a HELOC, it is important to understand exactly how its rate is calculated, how frequently it can change, and whether the lender offers any rate limits or fixed-rate options.
- How You Access the Money
The way you access borrowed funds is another important distinction.
With a home equity loan, you generally receive the borrowed amount upfront.
This can work well when you know exactly how much money you need.
For example, if you are completing a single large home renovation with a clearly established cost, receiving the entire amount at once may be convenient.
A HELOC provides a different type of access.
Instead of taking the entire amount immediately, you generally have a draw period during which you can access funds as needed.
This can be useful when expenses occur over time rather than all at once.
For example, suppose you are renovating a home and do not know exactly when every expense will occur. A HELOC may allow you to access funds as different expenses arise instead of borrowing the full amount at the beginning.
The source specifically explains that HELOC borrowers generally pay interest on the amount they have actually used rather than the entire available credit line.
That can make the structure more flexible than taking a large lump-sum loan when you do not immediately need all of the money.
However, flexibility should not be confused with unlimited borrowing.
A HELOC has a defined credit limit and specific terms governing how and when you can access the money.
- Draw Period vs. Repayment Period
A HELOC is usually divided into different stages.
The first is the draw period.
During this period, you can generally borrow from the available credit line according to the terms of the HELOC.
After the draw period ends, the loan enters its repayment stage.
The source describes a typical arrangement in which the draw period can be around 10 years, followed by a repayment period that may last around 20 years, although the exact periods vary by lender and loan terms.
This distinction is extremely important because your financial obligations can change when the draw period ends.
During the draw period, you may still have access to additional funds.
Once the repayment period begins, you generally cannot continue borrowing from the line in the same way, and the focus shifts toward repaying what you have borrowed.
This means you should not evaluate a HELOC only by looking at its initial monthly payment or introductory terms.
You need to understand what happens throughout the entire life of the credit line.
Ask the lender:
How long is the draw period?
How long is the repayment period?
Can the draw period be extended?
What happens to the interest rate after the draw period?
How will the monthly payment be calculated during repayment?
Understanding these details can help prevent unpleasant surprises later.
- Interest Is Based on What You Borrow
One of the most useful features of a HELOC is that you generally pay interest based on the amount you actually draw rather than the entire available credit limit.
Imagine that your HELOC has a $100,000 credit limit.
If you only borrow $20,000, you are not generally paying interest as though you had borrowed the full $100,000.
This is different from a traditional lump-sum loan where the entire borrowed amount is provided upfront.
That flexibility can be useful when you have uncertain or gradually occurring expenses.
However, it does not mean borrowing is free.
Once you draw money from the HELOC, that balance can generate interest according to the terms of the credit line.
And because many HELOCs use variable rates, the cost associated with that borrowed balance can change.
The source specifically points out that this flexibility is one reason a HELOC can differ from a home equity loan.
This makes it important to borrow only what you actually need.
A larger available credit line does not mean you should automatically use it.
- Qualification and Home Equity Requirements
Before you can borrow against your home’s equity, the lender needs to determine whether you qualify.
One important factor is how much equity you have in the property.
The source explains that lenders may want homeowners to have a certain minimum amount of equity, with some lenders looking for at least 15% to 20%. The exact requirement varies by lender and circumstances.
Generally, having more equity can give you more borrowing options.
Your credit profile also matters.
The source discusses a credit score of at least 620 as a possible benchmark, while noting that a higher score can make you a more attractive borrower.
Another important factor is your debt-to-income ratio, or DTI.
DTI compares your monthly debt obligations with your monthly income.
For example, your debts may include:
Mortgage payments
Car loans
Credit card payments
Child support
Alimony
Other recurring debt obligations
The lower your debt-to-income ratio, generally, the more manageable your existing obligations appear relative to your income.
The source discusses a DTI below 43% as a benchmark lenders may look for, although actual requirements can vary by lender and borrower.
Your credit score, income, existing debt, home equity, and other financial characteristics can all influence the terms you receive.
- Interest Rates Can Be Higher Than Your First Mortgage
A HELOC is a second mortgage, which means it sits behind your primary mortgage in the repayment hierarchy.
Because of this additional risk to the lender, HELOC interest rates can be higher than the interest rate on a typical first mortgage.
The source explicitly notes that second mortgages tend to carry higher rates because they are considered riskier than the primary mortgage.
This difference is important when evaluating whether borrowing against your home makes financial sense.
You should not compare the HELOC rate only with the rate on your existing mortgage and assume they will be identical.
They are separate financial products with different risk characteristics.
The rate you receive can also depend on your creditworthiness and the amount of equity you are accessing.
According to the source, stronger borrowers may qualify for better rates, while the amount of equity being borrowed can also affect the rate offered.
Because HELOC rates can be variable, you should also consider how your payment might change if interest rates rise.
- Fees and Other Loan Terms Matter
Interest rate is not the only thing you should compare when shopping for a HELOC or home equity loan.
Different lenders can structure their products differently.
For a HELOC, one important detail is whether the lender requires a minimum initial draw.
Some lenders may require you to borrow a certain amount when opening the credit line.
That could be inconvenient if you intended to use the HELOC primarily as an emergency backup and did not actually need the money immediately.
The source specifically warns borrowers to check the fine print for minimum initial draw requirements and possible fees or obligations associated with them.
Other terms can also matter, including:
Annual fees
Closing costs
Minimum borrowing requirements
Interest rate structure
Fixed-rate conversion options
Draw period
Repayment period
Borrowing limits
Early termination conditions
Potential penalties or other charges
When comparing lenders, do not automatically choose the lender offering the lowest advertised interest rate.
A slightly lower rate may not be the best deal if the product includes significant fees or restrictive terms.
The overall cost and flexibility of the loan matter.
- Risk: Your Home Is the Collateral
Perhaps the most important difference between ordinary unsecured borrowing and home equity borrowing is the collateral involved.
A HELOC and home equity loan use your home as collateral.
That means failing to repay the debt can put your home at risk.
The source emphasizes that this is a significant consideration. If a homeowner cannot repay the HELOC, the consequences can ultimately include losing the home.
This risk should be considered before borrowing.
A HELOC may provide access to substantial funds, but the money is not risk-free simply because you already own the property.
You are converting part of your home’s equity into debt.
That means the decision should be based on your ability to make the payments and the purpose of the borrowing.
Using home equity for a major improvement that contributes to the property may be very different from using it for discretionary spending.
The source specifically cautions against using a HELOC for things such as vacations or other purchases that do not contribute to wealth or the value of the home.
The fundamental rule is simple: understand that your home is securing the debt before you borrow.
Home Equity Loan vs HELOC: Quick Comparison
Home Equity Loan
Loan structure:
Lump sum
Access to funds:
Generally received upfront
Interest rate:
Often fixed, depending on the product
Payment structure:
Typically structured around repayment of the borrowed amount
Best suited to:
Known, one-time expenses where you know how much you need
Flexibility:
Lower than a HELOC because the money is generally borrowed upfront
Risk:
Your home serves as collateral
HELOC
Loan structure:
Revolving line of credit
Access to funds:
Borrow as needed during the draw period
Interest rate:
Often variable
Payment structure:
Changes based on the amount borrowed and applicable interest rate
Best suited to:
Expenses that occur over time or situations where borrowing needs are uncertain
Flexibility:
Higher because you can generally draw funds as needed during the draw period
Risk:
Your home serves as collateral
When a Home Equity Loan May Make More Sense
A home equity loan may be worth considering when you know exactly how much money you need.
Suppose you are planning a large renovation and have received a detailed estimate.
If the project will cost $60,000 and you need the entire amount immediately, a lump-sum home equity loan can provide a straightforward structure.
You receive the money and repay the loan according to its terms.
The fixed-rate structure commonly associated with home equity loans can also make budgeting easier because you have greater payment predictability.
However, the exact interest rate, fees, repayment period, and other conditions depend on the lender.
You should compare the total borrowing cost rather than focusing only on the monthly payment.
When a HELOC May Make More Sense
A HELOC may be more useful when you do not need all of the money at once.
For example, suppose you are completing a home improvement project over several months.
Instead of borrowing $80,000 immediately, you may need $15,000 initially, another $10,000 later, and additional amounts as the project progresses.
A HELOC can provide a pool of available credit from which you draw as needed during the draw period.
The source also explains that a HELOC may be useful for homeowners who want a potential emergency source of funds, particularly when a large amount of savings has been tied up in the home.
However, the possibility of having an emergency credit line should not encourage unnecessary borrowing.
You still need to consider interest costs, fees, variable rates, and the fact that your home is collateral.
Should You Use a HELOC for Home Improvements?
The source specifically discusses home improvements as an example of a use that can potentially make sense for a HELOC.
A significant renovation or repair can improve the usefulness or value of the property.
In that situation, borrowing against home equity can be connected to an asset you already own.
However, not every home improvement automatically increases a property’s value by more than the amount borrowed.
You should therefore evaluate the actual project cost and expected benefit instead of assuming that every renovation is financially worthwhile.
The source also notes that interest on a HELOC may be tax deductible when the money is used to substantially improve the home, subject to applicable tax rules.
Tax treatment can depend on the borrower’s circumstances and current tax law, so this should not be treated as a universal tax benefit.
If tax deductions are an important part of your decision, verify the rules applicable to your situation with a qualified tax professional.
When a HELOC May Not Be a Good Fit
A HELOC is not automatically the right choice simply because you have substantial home equity.
There are several situations where the structure may be less suitable.
Unstable income is one example.
Because a variable-rate HELOC can experience changes in interest costs, a borrower with uncertain income may have difficulty handling higher payments if rates increase.
The source specifically identifies unstable income as a reason to be cautious about using a HELOC.
A planned home sale is another consideration.
If you are planning to move soon, borrowing against your current home may create additional complications.
The HELOC generally needs to be paid off when the property is sold because the line is secured by that home.
This can result in an additional balance that must be settled during the sale.
A HELOC may also be less appropriate when you only need a relatively small amount of money.
The source points out that HELOCs can have startup costs, making another type of borrowing potentially more practical for smaller borrowing needs.
Finally, using a HELOC for discretionary spending such as vacations or expensive purchases deserves particular caution because you are putting your home behind the debt.
Why Some Homeowners Prefer a HELOC Over Cash-Out Refinancing
Homeowners have multiple ways to access home equity, including cash-out refinancing, home equity loans, and HELOCs.
A cash-out refinance replaces the existing mortgage with a larger mortgage and gives the borrower the difference in cash.
A HELOC does not replace the primary mortgage.
Instead, it creates an additional loan secured by the home’s equity.
This can be particularly relevant for homeowners who already have a favorable mortgage rate.
If you refinance the entire mortgage, you could potentially change the interest rate and terms on your original mortgage.
A HELOC allows the homeowner to access additional funds without replacing that primary mortgage.
The source specifically highlights this distinction and notes that homeowners with a favorable existing mortgage rate may prefer not to alter their primary mortgage when accessing equity.
However, a HELOC creates additional debt and a second lien against the property, so the decision should be evaluated based on the complete cost and risk.
How Much Can You Borrow?
The amount you can borrow through a HELOC or home equity loan depends on factors such as the value of your home, the amount of equity you have, your existing mortgage balance, your credit profile, income, debt obligations, and the lender’s rules.
The source notes that lenders may look for a minimum level of home equity and that having more equity can improve the number of options available.
It is important not to confuse your total home equity with the amount you can automatically borrow.
If your home is worth $400,000 and your mortgage balance is $200,000, your theoretical equity is $200,000.
That does not mean a lender will automatically allow you to borrow $200,000.
Lenders generally apply their own limits and underwriting requirements.
Your borrowing capacity will depend on the specific loan product and your financial profile.
Questions to Ask Before Borrowing Against Your Home
Before choosing between a home equity loan and HELOC, ask the lender for clear answers to the following:
What is the interest rate?
Is the rate fixed or variable?
How frequently can the rate change?
What is the maximum credit limit?
How much equity must I have?
What credit score is required?
What debt-to-income ratio is acceptable?
Are there application or closing costs?
Is there an annual fee?
Is there a minimum initial draw?
How long is the draw period?
How long is the repayment period?
What happens when the draw period ends?
Can I convert a variable balance to a fixed rate?
What happens if I sell my home?
Are there early termination costs?
What happens if interest rates increase?
What will my estimated payment be under different rate scenarios?
Getting these answers before signing can help you understand the full financial commitment.
Final Thoughts
A home equity loan and a HELOC both allow homeowners to borrow against the equity they have built in their homes, but the two products operate differently.
A home equity loan generally provides a lump sum and may offer a fixed interest rate, making it more predictable for a borrower who knows exactly how much money is needed.
A HELOC provides a revolving line of credit that allows the borrower to access funds over time. It can offer greater flexibility, but many HELOCs have variable interest rates, meaning borrowing costs can change.
The differences go beyond how you receive the money.
You also need to consider interest rate structure, draw and repayment periods, qualification requirements, fees, borrowing flexibility, tax considerations, and the risks associated with using your home as collateral.
Most importantly, home equity is not free cash.
When you borrow against your home, you are taking on additional debt secured by an asset that may be one of your most valuable financial possessions.
Before borrowing, make sure you understand how the payments fit into your budget and what could happen if your income changes or interest rates rise.
For a known, one-time expense, a home equity loan may provide a simpler structure.
For expenses that occur over time or situations where you want access to funds without borrowing the entire amount immediately, a HELOC may provide greater flexibility.
The right choice depends on the amount you need, how you plan to use the money, the terms you qualify for, and your ability to manage the debt.
Most importantly, compare multiple lenders, read the fine print, and understand the risks before turning your home equity into a new financial obligation.