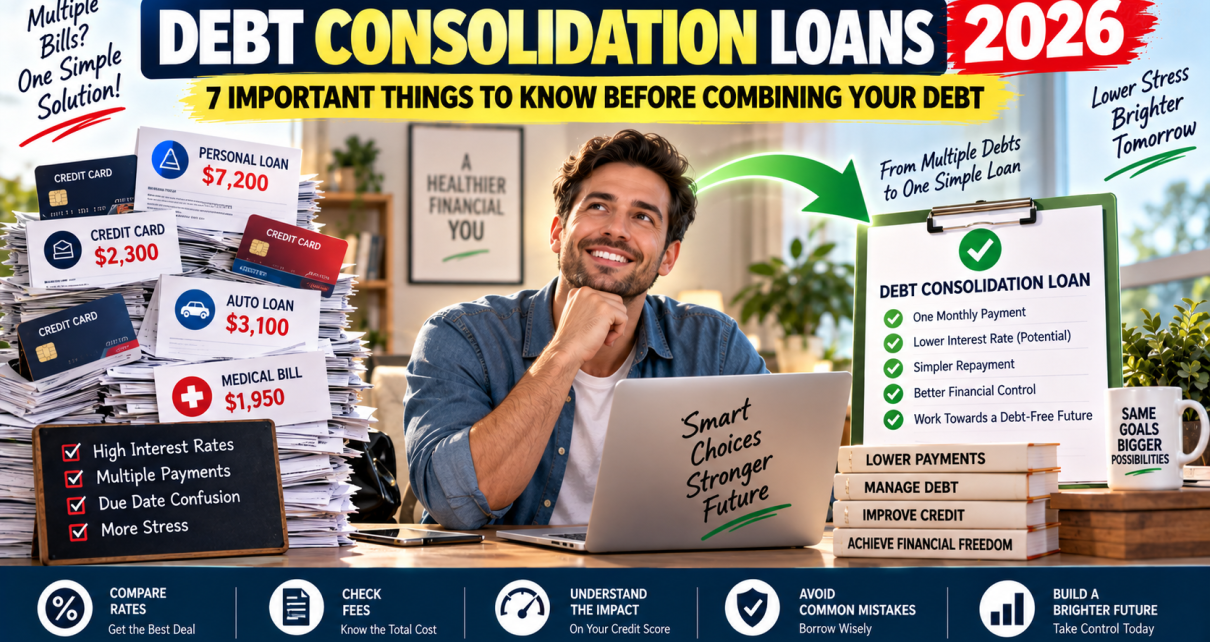
Debt Consolidation Loans 2026: 7 Important Things to Know Before Combining Your Debt
Managing multiple debts can become difficult quickly. Credit cards, personal loans, medical bills, and other balances can each have different interest rates, payment dates, and terms. Keeping track of everything can make debt repayment feel more complicated than it needs to be.
A debt consolidation loan is one option that can simplify this situation by combining multiple existing debts into one new loan.
Instead of making separate payments to several creditors, you use the new loan to pay off your existing balances and then make one monthly payment toward the consolidation loan.
But debt consolidation is not automatically the right solution for everyone.
The potential benefits depend on the interest rate you qualify for, the amount of debt you have, the repayment term, your ability to make the new monthly payment, and whether you can avoid accumulating new debt after consolidating.
Before combining your debt in 2026, there are several important things you should understand.
Here are seven key factors to consider before taking out a debt consolidation loan.
- Understand What a Debt Consolidation Loan Actually Does
A debt consolidation loan is a loan used to combine multiple existing debts into one new loan.
The source explains that these loans can be used to consolidate debts such as credit cards, personal loans, and medical bills. Instead of continuing to make multiple payments, you use the proceeds from the new loan to pay off your existing creditors.
For example, imagine you have four credit cards, each with a $5,000 balance.
That means you have a total of $20,000 in credit card debt.
Rather than continuing to manage four separate balances, you could potentially take out a $20,000 debt consolidation loan and use the proceeds to pay those cards off.
Afterward, you would have one new loan and one monthly payment.
The purpose is not to make the debt disappear.
You are still borrowing the money.
The difference is that the structure of your debt changes.
Instead of managing several separate accounts, you have one consolidated balance with one lender and one repayment schedule.
This can make debt management easier, but the financial benefit depends heavily on the terms of the new loan.
A consolidation loan is generally more useful when the new loan has a lower annual percentage rate than the debts you are replacing.
If the new interest rate is not meaningfully lower, consolidation may simplify your payments without producing much financial savings.
- Compare the Interest Rate Before You Consolidate
The interest rate is one of the most important factors to evaluate.
The source explains that debt consolidation can make sense when you qualify for a lower APR than the rates on your existing debts.
This matters because interest can significantly increase the total amount you pay over time.
Credit card balances, for example, can carry relatively high interest rates. If you qualify for a consolidation loan at a lower rate, more of your monthly payment can potentially go toward reducing the principal rather than paying interest.
Consider a simplified example.
Suppose you have several high-interest balances totaling $20,000.
If those balances carry high APRs and you qualify for a consolidation loan with a substantially lower APR, consolidating could reduce the amount of interest charged over the repayment period.
However, the interest rate alone does not tell the entire story.
You also need to consider:
The loan term
Origination or other fees
The required monthly payment
The total interest paid
Whether the rate is fixed
Your ability to make payments on time
A lower monthly payment is not necessarily evidence that you are saving money.
A longer repayment term can reduce your monthly payment while increasing the total amount of interest paid over the life of the loan.
That is why you should compare the total cost of the new loan with the cost of continuing your existing repayment plan.
- Look at the Repayment Term, Not Just the Monthly Payment
Debt consolidation loans typically come with a defined repayment period.
The source describes loan terms ranging from about two to seven years, depending on the loan.
The repayment period matters because it determines how long you will be making payments.
For example, suppose you consolidate your debt with a three-year loan.
If you make the required payments on time and do not add new debt, the loan is scheduled to be paid off at the end of those three years.
That can provide something many borrowers find valuable: a clear timeline.
Instead of carrying revolving credit card balances indefinitely, you have a specific repayment schedule.
However, extending the repayment period can have a downside.
A longer term may make the monthly payment more affordable, but you could pay interest for a longer period.
This creates an important trade-off between affordability and total cost.
Before accepting a consolidation loan, ask yourself two questions:
Can I comfortably afford the required monthly payment?
How much will I pay in total before the loan is completely repaid?
You need both answers.
A payment that technically fits your budget but leaves very little room for emergencies may still create financial pressure.
At the same time, a very long repayment term could keep you in debt longer than necessary.
The goal should be to choose a repayment structure that you can realistically maintain while moving toward becoming debt-free.
- Check Your Credit Before Applying
Your credit score and credit history can play an important role in determining whether you qualify for a debt consolidation loan and what interest rate you receive.
According to the source, borrowers with good to excellent credit, described there as a score of 690 or higher, generally have access to more lender options and may qualify for lower interest rates.
Borrowers with lower credit scores may have fewer options and may need to consider lenders that specialize in debt consolidation for borrowers with less-than-perfect credit.
This makes checking your credit before applying an important step.
Knowing your credit position gives you a better idea of what types of loan offers may be available.
It also helps you compare lenders more intelligently.
For example, if your credit is strong, you may want to shop around for the lowest available APR rather than accepting the first offer you see.
If your credit is weaker, you may need to pay closer attention to the total cost of borrowing and whether consolidation actually improves your financial position.
The source also discusses prequalification.
Prequalification can allow borrowers to get an idea of potential rates and terms before submitting a formal application. The source notes that this process can involve a soft credit check, which generally does not have the same impact as a hard credit inquiry.
However, prequalification is not the same as final approval.
A lender can still review your information more thoroughly during the formal application process.
- Make Sure the New Payment Fits Your Budget
A debt consolidation loan only helps if you can afford to repay it.
This may sound obvious, but it is one of the most important considerations.
The source specifically recommends checking whether you can comfortably make the new monthly payment within your budget before consolidating.
Before applying, calculate your monthly income and necessary expenses.
Then consider the new loan payment alongside your existing financial obligations.
Do not evaluate the payment in isolation.
Your budget may include:
Housing costs
Utilities
Food
Transportation
Insurance
Existing debt payments
Childcare
Taxes
Savings
Other recurring expenses
After accounting for these obligations, determine whether the consolidation payment is realistically affordable.
The purpose of consolidation should be to create a manageable path toward paying off debt, not to replace several difficult payments with one payment that is equally difficult or even harder to maintain.
You should also consider whether the consolidation loan will actually cover all of your existing debt.
The source recommends making a complete list of your debts and ensuring that the new loan is sufficient to cover the combined amount you intend to consolidate.
If some balances remain outside the consolidation, you may still have multiple payments afterward.
A complete debt inventory can help you understand exactly what you are consolidating and what will remain.
- Debt Consolidation Does Not Fix Overspending
One of the biggest misconceptions about debt consolidation is that getting a new loan solves the underlying reason the debt accumulated.
It does not.
A consolidation loan changes the structure of your debt.
It does not automatically change your spending habits.
The source directly warns that debt consolidation does not address spending behavior that created the debt in the first place.
This is especially important with credit card debt.
Imagine you use a consolidation loan to pay off several credit cards.
Your credit card balances may now be zero.
But if you immediately begin using those cards again without changing your budget, you could end up with both the new consolidation loan and new credit card balances.
That can make your financial situation worse rather than better.
For consolidation to work effectively, you generally need a realistic plan for managing your spending after the existing debt is paid off.
That could include:
Creating a monthly budget
Reducing unnecessary expenses
Avoiding new credit card balances
Building an emergency fund
Tracking your spending
Setting a specific debt payoff goal
The source emphasizes the importance of creating a realistic budget and sticking to it.
Consolidation should therefore be viewed as a debt-management tool, not a replacement for financial discipline.
- Know When Debt Consolidation May Not Be the Right Choice
Debt consolidation can be useful in the right circumstances, but there are situations where it may not make sense.
The first is when your existing debt is already small enough to repay relatively quickly.
The source gives the example of debt that could be paid off within roughly six months to a year at your current pace. In that situation, the potential savings from consolidation may be relatively small.
If the debt will disappear quickly anyway, taking out a new loan may introduce additional complexity without providing a meaningful financial benefit.
Another situation is when your debt burden is overwhelming.
The source notes that if your total debt is more than half of your income and even reduced payments do not appear manageable, debt relief may need to be considered instead of simply consolidating the balances.
This is an important distinction.
Debt consolidation works by reorganizing debt.
It does not eliminate the debt.
If your income is not sufficient to support the required payments, changing the loan structure may not solve the underlying problem.
In such circumstances, exploring other forms of debt assistance may be more appropriate.
Alternatives to a Debt Consolidation Loan
A consolidation loan is only one possible strategy for dealing with debt.
Depending on your circumstances, other options may include a balance transfer credit card, refinancing certain debt, borrowing from family or friends, using home equity, or taking a loan against a retirement account.
The source specifically mentions several of these alternatives.
Each alternative has different eligibility requirements, costs, risks, and consequences.
For example, a balance transfer credit card may offer a promotional interest rate for a specific period, but the borrower needs to understand the promotional terms and what happens afterward.
Using home equity can provide access to funds, but it also means putting your home at risk if the debt is not repaid.
A retirement-account loan has its own rules and potential consequences.
The right alternative therefore depends on your financial circumstances.
Do not assume that because a particular strategy works for one borrower, it will automatically work for you.
How to Apply for a Debt Consolidation Loan
If you decide that consolidation may be appropriate, the application process generally begins with understanding your financial position.
Start by checking your credit score and credit history.
Next, make a complete list of your existing debts.
For each balance, record:
Current balance
Interest rate
Minimum monthly payment
Lender
Remaining repayment period
This information gives you a clear picture of what you are currently paying.
Then compare potential consolidation loans.
Look at the APR, loan amount, repayment term, monthly payment, fees, and total repayment cost.
Prequalification can help you compare potential offers before submitting a formal application, depending on the lender.
Once you identify an option that appears suitable, you can submit the formal application.
The source notes that formal applications generally require personal financial information and a hard credit check, and that lenders may approve applications within approximately seven to ten days, although actual timing can vary.
Do not rush the process simply because you want to eliminate multiple payments quickly.
Comparing offers can be one of the most valuable steps.
A slightly better interest rate or more suitable repayment term can make a meaningful difference over several years.
Debt Consolidation Example
Consider a borrower with four credit cards.
Each card has a $5,000 balance.
That creates a total of $20,000 in credit card debt.
Instead of making four separate payments, the borrower applies for a $20,000 debt consolidation loan.
If approved, the borrower uses the loan proceeds to pay off the four credit cards.
The borrower now has one loan and one scheduled monthly payment.
The source uses essentially this example to explain how consolidation changes the structure of the debt.
But the example does not automatically mean consolidation is financially beneficial.
To determine whether it makes sense, the borrower would need to compare the new loan’s APR and total repayment cost against the existing credit card debt.
The borrower would also need to determine whether the new monthly payment fits comfortably within the household budget.
Finally, the borrower would need to avoid rebuilding the credit card balances after they are paid off.
That final point is critical.
The success of consolidation depends not only on the loan terms but also on what happens afterward.
Potential Benefits of Debt Consolidation
When the numbers work, debt consolidation can provide several practical benefits.
First, it can simplify debt management.
Instead of tracking several payments, you may have one monthly payment.
Second, it can potentially reduce interest costs if the new loan has a lower APR than your existing debts.
Third, it can provide a defined repayment timeline.
For example, a three-year consolidation loan gives you a specific repayment schedule rather than leaving revolving debt open-ended.
Fourth, successfully managing the new loan and making payments on time may contribute to healthier credit over time, while keeping credit card balances low can also be beneficial. The source notes that successful consolidation can potentially improve credit when payments are made on time and card balances remain low.
However, these potential benefits depend on the borrower’s actual behavior and the terms of the loan.
Potential Drawbacks of Debt Consolidation
Consolidation also has potential disadvantages.
You may pay fees when taking out the new loan.
A longer repayment term could mean paying interest for a longer period.
If the new interest rate is not lower than your existing rates, there may be little financial benefit.
You may also become tempted to use credit cards again after paying them off.
That can create a particularly difficult situation because you could end up with both the consolidation loan and new revolving debt.
Another concern is that consolidation can create a false sense that your debt problem has been solved.
The debt has only been reorganized.
The balance still has to be repaid.
This is why the source emphasizes that budgeting and controlling spending remain important even after consolidation.
Final Thoughts
A debt consolidation loan can be a useful tool for borrowers who are dealing with multiple debts and want to simplify their repayment strategy.
Instead of managing several balances and payment dates, you may be able to combine eligible debts into one loan with one monthly payment.
The potential financial advantage is strongest when the consolidation loan provides a lower APR than your existing debts and the new monthly payment comfortably fits within your budget.
But consolidation is not a universal solution.
Before applying, check your credit, list all of your debts, compare interest rates and repayment terms, calculate the total cost, and make sure the new payment is affordable.
Most importantly, address the spending habits that contributed to the debt.
If you pay off your credit cards through consolidation but immediately begin accumulating new balances, you may end up deeper in debt.
For borrowers with manageable debt, a consolidation loan may provide a structured path toward becoming debt-free.
For someone whose debt is overwhelming or whose income cannot support the required payments, simply replacing several debts with one loan may not be enough.
The goal should not be merely to have fewer payments.
The goal should be to create a realistic and sustainable plan for paying off your debt.
Before combining your debt in 2026, look carefully at the interest rate, repayment period, fees, monthly payment, and your overall financial situation. If the numbers work and you can maintain disciplined spending, consolidation may make debt management simpler and give you a clearer path toward becoming debt-free.