Business Line of Credit vs Business Credit Card 2026: 9 Key Differences for Small Businesses
Small businesses often need extra capital to keep operations running smoothly, but not every expense calls for the same type of financing.
When evaluating a business line of credit vs business credit card, it helps to realize that both provide flexible borrowing power, but they serve entirely different day-to-day functions. A credit card excels at covering routine recurring expenses like software subscriptions and office supplies. A line of credit, on the other hand, acts as a pool of capital designed to fund inventory, plug seasonal cash flow gaps, or meet payroll during slow months.
Understanding how these two tools differ in structure, interest calculations, and convenience will help you choose the right product for your cash-flow cycle. Here are nine key differences every small business owner should consider.
-
Primary Purpose and How Funds Are Used
The simplest distinction lies in how you deploy the capital.
A business credit card is designed for direct spending. You swipe or enter the card details to pay vendors, buy office supplies, pay utility bills, or cover digital marketing expenses.
A business line of credit functions as a flexible reserve of cash. Instead of paying a supplier directly with a card, you draw funds from your credit limit and deposit them directly into your business checking account. From there, you can write checks, send bank wires, or issue direct deposits for larger operational needs like payroll, equipment repairs, or bulk inventory purchases.
-
How You Access the Money
With a credit card, fund access is instantaneous at the point of sale. You make a purchase, it posts to your statement, and you pay it down later.
Accessing a line of credit requires an intentional draw request. You log into your commercial banking portal and transfer a specific dollar amount into your checking account. Depending on your lender and transfer method, this process can take anywhere from a few minutes to two business days. If a supplier demands immediate payment on the spot, a credit card is usually far more convenient.
-
How Interest Accrues on Unused Funds
One major benefit of a business line of credit is that you only pay interest on the money you actively draw, not the total approved limit.
For example, if you hold a $20,000 credit line but only transfer $3,000 to cover an unexpected repair, interest only charges accumulate on that $3,000. The remaining $17,000 sits available without incurring daily interest.
A business credit card works similarly regarding your total credit limit. However, card purchases typically benefit from a grace period. If you pay your statement balance in full every month by the due date, you can avoid paying interest on purchases altogether.
-
Stated Interest Rates vs. Total Cost
Business credit cards typically carry higher ongoing interest rates (APRs) than business lines of credit. However, a higher stated rate does not automatically make the credit card more expensive.
If you pay your credit card balance in full every billing cycle, you pay zero interest. In that scenario, the credit card is effectively free short-term financing.
Conversely, interest on a line of credit usually begins accruing the moment funds land in your bank account. If you draw $5,000 from a credit line with a lower interest rate but take six months to repay it, you will accumulate real interest charges. The cheaper option depends entirely on how quickly you repay the borrowed funds.
-
Balance Management and Reusability
Both tools offer revolving credit, meaning as you pay down what you owe, your available credit replenishes.
With a credit card, managing the balance revolves around your monthly billing statement and grace period. Carrying a revolving balance month-to-month can quickly get expensive due to compound interest.
With a line of credit, repayments are structured around weekly or monthly installments until the drawn amount is cleared. Once repaid, that portion of the line becomes available to draw again. However, some lines of credit charge draw fees or maintenance fees, which means reusing the line incurs minor transactional costs.
-
Point-of-Sale Convenience
For small, frequent business purchases, credit cards are vastly superior. Charging a client lunch, purchasing a monthly SaaS membership, or buying printer paper takes seconds.
Using a line of credit for minor expenses is inefficient. Initiating a bank transfer just to pay a $50 subscription creates unnecessary administrative work. Credit cards are built for transactional convenience; credit lines are built for liquidity management.
-
Ideal Expense Sizes
Matching the loan product to the size of the purchase prevents unnecessary borrowing costs.
Credit cards work best for small to mid-sized expenses that fit comfortably within your monthly revenue cycles.
Lines of credit excel at larger operational funding gaps. Expenses like buying a delivery vehicle, purchasing seasonal inventory, or paying contractor invoices before client payments arrive are far better suited for a credit line.
-
Total Borrowing Cost Structure
To calculate the true cost of borrowing, look beyond advertised interest rates and evaluate the entire borrowing cycle.
When choosing between these options, a business owner should consider:
-
How long the balance will remain outstanding before being fully repaid.
-
Whether the credit card provider offers an interest-free grace period on purchases.
-
Origination, draw, or monthly maintenance fees associated with the line of credit.
-
Annual fees or rewards programs on the business credit card that offset costs.
A lower interest rate on a credit line can easily cost more in total dollars if the funds sit unpaid for months while incurring draw fees.
-
Matching Funding to Specific Expenses
Giving each financial tool a specific role prevents cash-flow confusion and keeps borrowing costs predictable.
A business credit card is ideal for routine expenses such as:
-
Monthly software subscriptions and web hosting fees.
-
Office supplies, utilities, and telecom bills.
-
Client entertainment, business meals, and travel expenses.
-
Online digital marketing and advertising spend.
A business line of credit is better suited for needs such as:
-
Buying bulk inventory ahead of peak sales seasons.
-
Covering payroll during slow cash-flow months.
-
Emergency equipment repairs or building maintenance.
-
Upfront costs for large client contracts before milestone payments land.
Business Line of Credit vs Business Credit Card: Quick Comparison
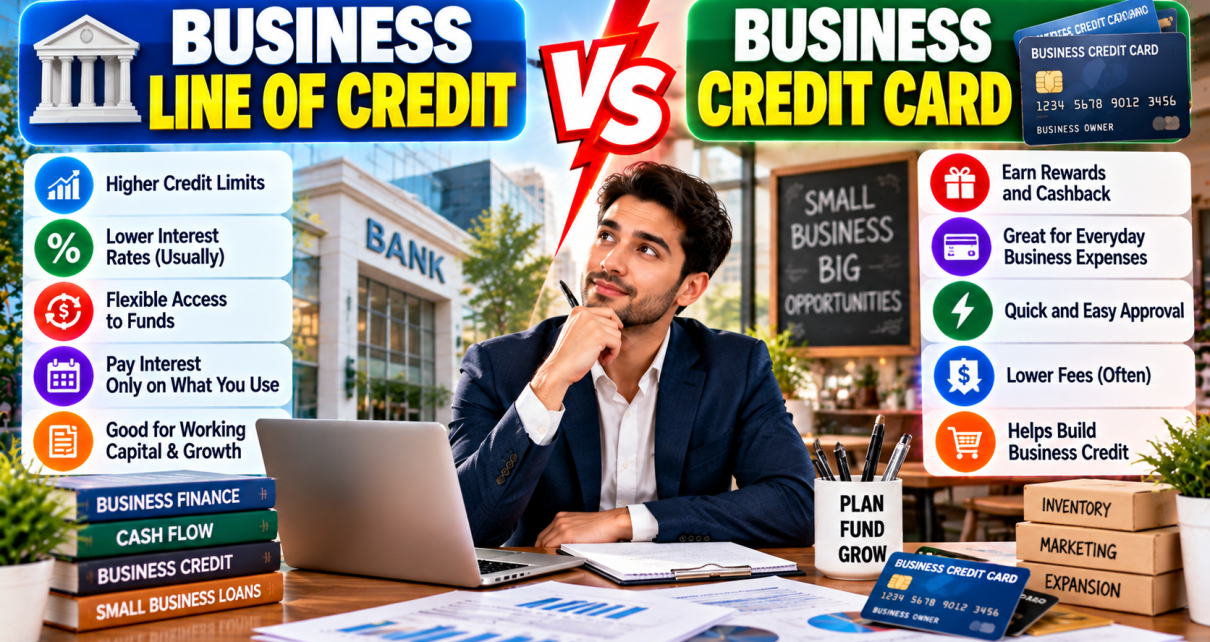
A business credit card serves primarily as a payment method. It streamlines daily purchasing, provides transaction tracking, and often offers cash-back or travel rewards. However, carrying a balance from month to month can become costly.
A business line of credit serves primarily as working capital backup. It offers cash flexibility for bigger expenses, but drawing money requires an extra step and incurs interest immediately upon transfer.
Questions to Ask Before Choosing
Before submitting an application for either option, evaluate your financial pipeline by asking:
-
How much money do I actually need to borrow right now?
-
How quickly will my business generate the revenue needed to repay the balance?
-
What fees (annual fees, draw fees, wire transfer fees) apply to each product?
-
Does my cash-flow cycle fluctuate seasonally, or is it steady month-to-month?
-
Am I looking for purchasing convenience or cash reserves?
Common Mistakes Small Businesses Should Avoid
One common mistake is selecting a credit product based solely on the advertised interest rate. A low rate on a credit line can still cost more than a credit card if you carry the balance for a prolonged period and incur draw fees.
Another mistake is treating a line of credit like extra revenue sitting in your bank account. Drawn funds represent debt that must be repaid with interest.
Similarly, using a business credit card for large, long-term expenses without a clear payoff strategy can leave your company trapped under high-interest revolving debt.
Which One Should Your Small Business Use?
If your primary goal is managing daily spending, tracking employee expenses, and earning rewards on routine purchases, start with a business credit card.
If your primary goal is securing cash reserves to cover operational gaps, fund inventory, or manage unpredictable receivables, apply for a business line of credit.
Many established small businesses ultimately maintain both. They use the credit card for daily purchasing convenience and keep a business line of credit on standby for cash-flow protection.
Final Thoughts
Neither a business line of credit nor a business credit card is inherently better than the other. They are distinct financial tools designed for different business needs.
A credit card provides seamless purchasing power for recurring operational expenses. A line of credit delivers liquid capital to handle larger operational challenges. By matching the right tool to the specific expense and maintaining a clear repayment plan, you can protect your cash flow and keep borrowing costs under control.