Home Equity Loan vs. Cash-Out Refinance 2026: Which Option Fits Your Situation?
Your home may be one of your largest financial assets, but turning that equity into usable cash requires careful calculation. Both a home equity loan and a cash-out refinance give you access to a substantial amount of money, yet they operate in fundamentally different ways.
The primary difference comes down to what happens to your existing mortgage.
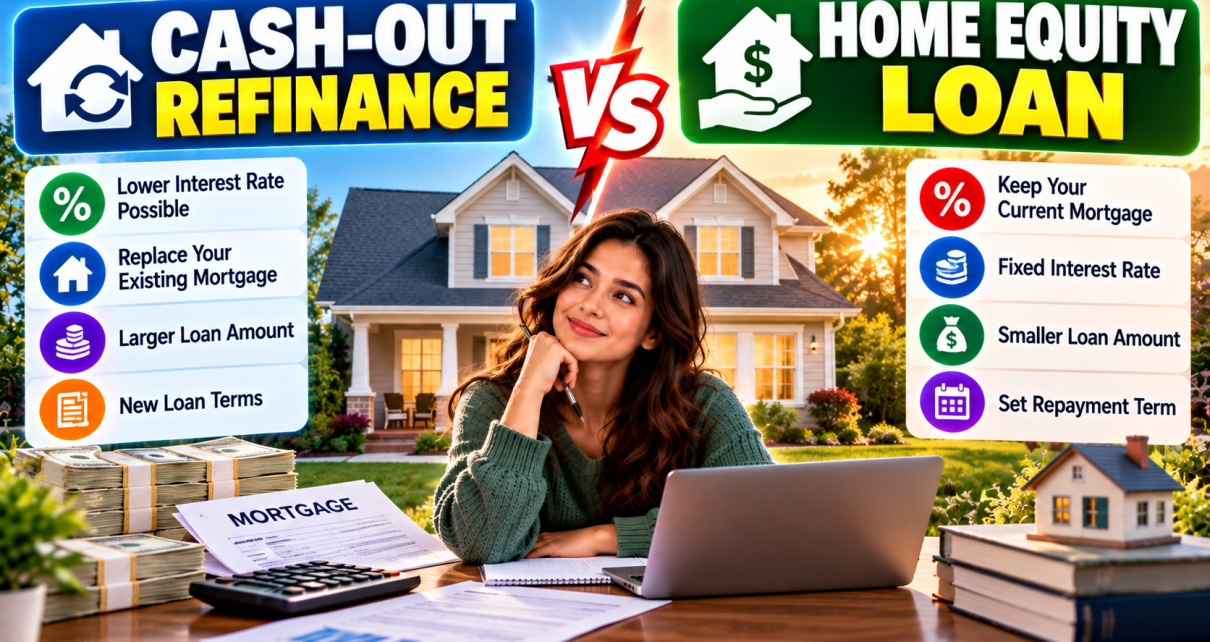
With a home equity loan, you keep your current mortgage exactly as it is and take out a separate, second loan secured by your property. You will have two distinct monthly payments.
With a cash-out refinance, your existing mortgage is entirely wiped out and replaced with a new, larger loan. This new mortgage pays off your old balance, and the lender hands you the remaining difference in cash.
That single structural difference drastically affects your interest rate, monthly obligations, closing costs, and the total lifetime cost of your debt. Choosing the right path depends heavily on the rate you currently hold, how much cash you need, and your timeline for paying it back.
Understanding the Home Equity Loan
A home equity loan allows you to borrow a lump sum against the ownership stake you have built in your property. Equity is simply the difference between your home’s current market value and the amount you still owe the bank.
If your property is worth $400,000 and your mortgage balance sits at $200,000, you have $200,000 in raw equity. A home equity loan gives you access to a portion of that money.
Because your original mortgage remains untouched, a home equity loan is considered a second mortgage. It sits in a junior lien position. From a lender’s perspective, second mortgages carry slightly higher risk, which often translates to a slightly higher interest rate compared to primary mortgages. However, they usually offer fixed rates, giving you a predictable monthly payment.
When the Second Mortgage Approach Makes Sense
Leaving your original mortgage intact is incredibly valuable if you locked in a remarkably low interest rate years ago.
Suppose you currently have a 30-year fixed mortgage at 3.5 percent. Market rates in 2026 may be hovering much higher. If you need $50,000 for a kitchen renovation, wiping out that 3.5 percent rate to refinance your entire home at a higher modern rate could cost you tens of thousands of dollars in unnecessary interest.
A home equity loan allows you to borrow just the $50,000 at current market rates while preserving that ultra-low rate on the bulk of your housing debt. It is an ideal solution for homeowners who need a specific, one-time lump sum and want to protect their primary loan terms.
Understanding the Cash-Out Refinance
A cash-out refinance takes a completely different route. Instead of adding a second loan, you restart the clock with a brand new, larger primary mortgage.
Imagine you owe $200,000 on your current mortgage and want to extract $75,000 in cash. A cash-out refinance replaces your old debt with a new $275,000 loan (plus closing costs). You use the new loan to pay off the old one, pocket the $75,000, and move forward making one single monthly payment.
Because you are originating a brand new primary mortgage, everything resets. You get a new interest rate, a new repayment term (such as 15 or 30 years), and you will pay standard refinancing closing costs, which typically range from 2 to 6 percent of the total loan amount.
When Replacing Your Mortgage Makes Sense
A cash-out refinance becomes highly attractive when current market rates are lower than the rate you are currently paying.
Consider a homeowner who bought a house a few years ago with a 7.5 percent mortgage rate. If rates drop closer to 5.5 percent, and the home has increased in value, a cash-out refinance achieves two goals at once. The homeowner can pull out cash to pay for a child’s college tuition while simultaneously lowering the interest rate on their entire housing debt.
The actual financial benefit still depends heavily on the closing costs and the new loan term. Extending a loan back out to 30 years might lower the monthly payment, but it frequently increases the total amount of interest paid over the life of the loan.
The Hidden Risks of Tapping Home Equity
No matter which route you choose, converting home equity into liquid cash carries serious risks. Both options use your house as collateral.
If you use a cash-out refinance or a home equity loan to pay off high-interest credit card debt, you are moving unsecured debt into secured debt. While the interest rate will likely drop, the stakes become much higher. If you face an unexpected financial crisis and cannot make the new mortgage payments, the lender can foreclose on your home.
Furthermore, draining your equity leaves you vulnerable to market downturns. If property values drop, borrowing too heavily could leave you owing more than the house is worth, making it difficult to sell or refinance later.
Actionable Checklist for Comparing Your Options
Before signing any loan documents, run your specific numbers through this diagnostic checklist:
-
Check your current rate: Find your exact current mortgage rate and remaining balance. If your rate is significantly lower than current market offerings, lean toward a home equity loan.
-
Calculate total closing costs: Refinance closing costs apply to the entire new loan amount, whereas home equity loan fees only apply to the smaller borrowed amount. Compare the two side-by-side.
-
Evaluate the timeline: How long do you plan to stay in the home? If you plan to sell in two years, the steep closing costs of a cash-out refinance may not be worth the short-term cash access.
-
Test your budget: Calculate your exact new monthly obligations. Can you comfortably manage the payments if your household income drops unexpectedly?
-
Shop multiple lenders: Do not accept the first quote you receive. Check with your current loan servicer, local credit unions, and online lenders to compare rates and origination fees.
The Bottom Line
There is no single winner between a home equity loan and a cash-out refinance. The smarter choice depends entirely on the math behind your specific situation.
A home equity loan is generally the preferred tool when you want to protect a low existing mortgage rate and only need to finance a specific project. A cash-out refinance is often the better strategy when market rates have dropped below your current rate, allowing you to restructure your entire debt while accessing the cash you need.
Calculate the upfront fees, weigh the long-term interest costs, and critically evaluate your ability to handle the payments. Your home equity is a powerful financial tool, but it should be utilized to build long-term stability, not to fund short-term lifestyle expenses.