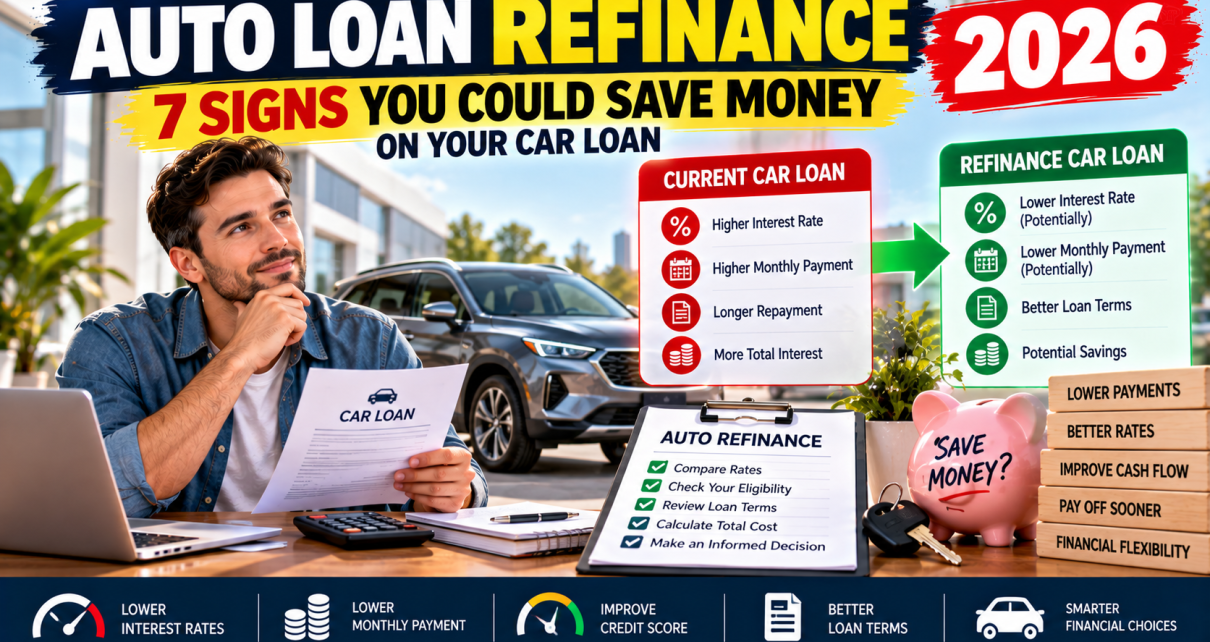
Auto Loan Refinance 2026: 7 Signs You Could Save Money on Your Car Loan
Refinancing an auto loan can be a useful way to reduce the cost of financing a vehicle, but it is not automatically a money-saving move for every borrower.
The basic idea is simple: you replace your existing car loan with a new loan, ideally with better terms. Depending on your circumstances, refinancing may help you obtain a lower interest rate, reduce your interest costs, or adjust the repayment schedule.
But there is an important distinction between lowering your monthly payment and actually saving money.
A longer loan term can reduce the amount you have to pay each month while increasing the amount of interest you pay over time. Since vehicles also lose value as they age, extending an auto loan unnecessarily can increase the risk of owing more than the vehicle is worth.
That is why it is important to look at the entire loan rather than focusing only on the monthly payment.
If you are considering refinancing your car loan in 2026, here are seven signs that it may be worth exploring.
- Your Current Interest Rate Is Higher Than What You Could Qualify For
The clearest reason to refinance an auto loan is the possibility of getting a lower interest rate.
If your current car loan has a relatively high APR and your financial profile has improved since you originally borrowed the money, refinancing may give you an opportunity to reduce your borrowing costs.
The source highlights this as the primary reason to refinance: replacing an existing loan with one carrying a better interest rate can reduce interest costs and potentially lower the monthly payment.
Consider a simplified example.
Suppose you still owe $20,000 on your vehicle and have three years remaining on the loan at an 11% interest rate.
If you could refinance the remaining balance at 5% for the same three-year period, the interest portion of your payments could be substantially lower.
The exact savings would depend on the remaining balance, loan terms, fees, and the rate you actually receive.
The important point is that refinancing works best when the new loan meaningfully improves the financial terms of the old one.
Before refinancing, compare the new APR with your existing APR and calculate the total interest you expect to pay under both scenarios.
Do not assume that a lower advertised rate automatically means you will save money.
The new loan could have fees, a different term, or other conditions that affect the total cost.
- Your Credit Has Improved Since You Bought the Car
Your credit profile can have a significant effect on the interest rate available to you.
When you originally financed your vehicle, your credit score may have been lower than it is today.
Perhaps you have since made your payments consistently, reduced other debts, or established a stronger credit history.
If your credit has improved, it may be worth checking whether you now qualify for better auto loan terms.
The source specifically points out that borrowers who have made payments on time and improved their credit may have an opportunity to qualify for a better rate when refinancing.
This is one reason refinancing should not necessarily be viewed as something you only consider when you are struggling with your existing loan.
It can also be a financial review opportunity.
If your creditworthiness has improved substantially, the terms available to you today may be different from those available when you purchased the vehicle.
However, a higher credit score does not guarantee approval or a specific interest rate.
Lenders also consider other factors, including income, existing debt, the vehicle, the remaining loan balance, and their own underwriting requirements.
The best way to find out whether refinancing could benefit you is to compare actual offers.
- Your Current Loan Has a Longer Term Than You Need
A lower monthly payment can be tempting, but it does not necessarily mean a loan is cheaper.
One way borrowers can reduce their monthly payment is by extending the repayment period.
For example, a loan with three years remaining could potentially be refinanced into a much longer term.
That could make the monthly payment smaller.
But the borrower may pay interest for a longer period.
The source warns against focusing solely on a lower monthly payment when the reduction comes from stretching the loan over a longer period.
This is especially important with vehicles because cars are depreciating assets.
Unlike an asset that may increase in value, a typical vehicle generally loses value as it gets older and accumulates mileage.
If your loan balance declines slowly while the vehicle’s value falls more quickly, you could eventually owe more than the vehicle is worth.
This situation is commonly referred to as being “upside down” or having negative equity.
A longer loan term can increase that risk because you are spreading repayment over more time.
If you refinance, consider whether you can choose a term that is the same length as the remaining term on your current loan or shorter.
A shorter term may result in a higher monthly payment, but it can reduce the amount of time you remain in debt and potentially reduce total interest.
The right choice depends on what you can comfortably afford.
- Your Monthly Payment Is Difficult to Manage
Another possible reason to consider refinancing is that your existing car payment is putting too much pressure on your budget.
A new loan with different terms could potentially reduce the required monthly payment.
However, this is where you need to be especially careful.
A lower payment can result from a lower interest rate, but it can also result from extending the loan term.
Those two situations are very different.
Suppose you have three years remaining on your auto loan.
If you refinance the balance over six years, your required monthly payment may fall because you are spreading the balance over twice as much time.
But that does not necessarily mean you are receiving a better financial deal.
You could end up paying interest for several additional years.
The source specifically cautions against extending a car loan simply to make the payment more affordable and suggests considering whether keeping the vehicle or selling it is financially sustainable if the payment is genuinely unaffordable.
If you are considering refinancing because your payment is difficult to manage, compare the total cost of the new loan.
Ask:
How much will I pay each month?
How many months will I make payments?
What is the new interest rate?
How much interest will I pay in total?
Will I owe more than the car is worth for longer?
A lower monthly payment is useful only if the overall financial structure makes sense.
- You Want to Reduce the Risk of Negative Equity
Negative equity is an important issue with auto loans.
A vehicle can depreciate while you are still making payments.
If the loan balance is higher than the car’s current market value, you are considered to have negative equity.
For example, imagine that your vehicle is worth $15,000 but you still owe $18,000.
You have $3,000 of negative equity.
This can become a problem if you want to sell or trade the vehicle because the proceeds from the sale may not be enough to pay off the loan.
The source emphasizes that longer auto loans can increase the risk of becoming upside down because the vehicle can depreciate faster than the loan balance is reduced.
This is why refinancing should not automatically involve extending the loan term.
If you can refinance at a lower rate while maintaining the same repayment period—or choosing a shorter period—you may be able to reduce interest costs without unnecessarily extending the debt.
A shorter loan term can also accelerate the reduction of your outstanding balance.
Of course, a shorter term generally means a higher monthly payment, so you need to make sure it fits within your budget.
The goal is to balance affordability with the speed at which you want to eliminate the debt.
- You Have Considered the Costs of Refinancing
A refinancing offer can look attractive because of its interest rate, but fees can reduce or even eliminate the potential savings.
Before signing a new auto loan, review the lender’s terms carefully.
The source specifically warns borrowers to look for costs such as prepayment penalties and origination fees. It notes that origination fees can be calculated as a percentage of the loan amount.
For example, imagine you refinance $10,000 and the new lender charges a 5% origination fee.
That would represent a $500 fee.
If your expected interest savings are only a few hundred dollars, the refinancing transaction may not actually save you money.
This is why you should calculate your net savings rather than comparing interest rates alone.
Your calculation should consider:
Current remaining balance
Current interest rate
Remaining term
New interest rate
New loan term
Origination fees
Application or other lender fees
Potential prepayment penalties
Total interest under the current loan
Total interest under the new loan
The exact fee structure varies between lenders, so read the loan agreement carefully.
You should also check whether your current loan has any conditions related to early payoff.
A refinancing lender is effectively paying off your existing loan, so you want to understand whether the existing lender charges any fee for that payoff.
A refinancing decision should be based on the total financial impact.
- You Can Get a Better Loan Without Taking Unnecessary Cash Out
Some lenders may offer a cash-out auto refinance, where you borrow more than your existing loan balance and receive the difference in cash.
The source provides an example in which a borrower owes $10,000 on a vehicle worth $15,000 and refinances for $12,000, receiving the additional $2,000 as cash.
This may sound attractive because it provides access to money, but it also increases the amount of debt secured by the vehicle.
You are paying interest on the additional money you borrow.
That means cash-out refinancing should be evaluated differently from refinancing purely to reduce your interest rate.
If your main goal is to save money, increasing the loan balance may work against that objective.
There can be situations where someone uses borrowed funds to pay off higher-interest debt, but that strategy should be analyzed carefully.
The key question is whether the additional borrowing actually improves your overall financial position after accounting for the new loan’s interest and fees.
Remember that the vehicle is a depreciating asset.
Keeping the amount owed as low as practical can help reduce the risk of owing more than the car is worth.
How to Refinance an Auto Loan
If you decide that refinancing could make financial sense, the process generally involves several steps.
Start by reviewing your current loan.
Find out:
Your remaining balance
Your current APR
Your remaining term
Your current monthly payment
Any payoff requirements or fees
Then review your credit profile.
If your credit has improved since you originally financed the vehicle, you may have a better chance of qualifying for more favorable terms.
Next, compare lenders.
The source suggests checking options such as local credit unions and online lenders.
Do not rely on a single lender.
Different lenders can evaluate borrowers differently and may offer different interest rates, repayment terms, and fees.
When comparing offers, look beyond the advertised APR.
Review the complete loan agreement.
Pay attention to:
Interest rate
Loan term
Monthly payment
Origination fees
Prepayment penalties
Other charges
Total repayment amount
Once you identify a loan that genuinely improves your financial position, you can proceed with the formal application.
Make sure the transition from your old loan to the new loan is handled correctly.
The source specifically warns borrowers to pay attention to payment timing when refinancing around the due date of an existing loan. An incorrectly timed payoff or missed payment could create unnecessary problems.
Do not assume the old loan has been completely paid off until you have confirmation.
Should You Refinance Just to Lower the Monthly Payment?
This is one of the most important questions to ask.
A lower monthly payment can improve your short-term cash flow.
But it does not necessarily reduce the overall cost of the car.
Suppose your current loan has three years remaining.
You refinance into a six-year loan.
Your monthly payment may fall significantly.
However, you have now committed yourself to payments for another three years beyond your original schedule.
You may also pay more total interest.
The source strongly emphasizes this distinction and warns against being misled by a lower payment created simply by extending the loan.
If you are refinancing, compare the total cost of both loans.
If the goal is to save money, a shorter or similar repayment period combined with a lower interest rate may be more consistent with that objective than simply stretching the debt out.
What Credit Score Do You Need to Refinance?
There is no single credit score that guarantees approval for every auto refinance loan.
However, your credit profile is an important part of the application.
The source emphasizes that good credit can help borrowers qualify for better rates and that making existing loan payments on time can help strengthen credit over time.
If your credit has improved since you purchased the car, refinancing may be worth investigating.
If your credit is weak, refinancing may still be possible with certain lenders, but the available rates may not produce meaningful savings.
A higher interest rate on the new loan could defeat the purpose of refinancing.
That is why you should compare the actual offer rather than assuming that refinancing will automatically produce a lower rate.
Should You Use a Cosigner?
A cosigner with stronger credit can potentially help a borrower qualify for better loan terms.
The source mentions a cosigner as one possible route for borrowers who do not have strong credit themselves.
However, adding a cosigner creates a significant financial responsibility for that person.
The cosigner may become responsible for the debt if the primary borrower fails to make payments.
Because of that, this option should be approached carefully and only after both parties understand the obligations created by the loan.
The potential benefit of improved qualification should be weighed against the financial responsibility being shared.
How Much Could You Save by Refinancing?
The amount you could save depends entirely on your individual loan.
Several variables matter:
Remaining balance
Current APR
New APR
Remaining term
New term
Fees
Payment schedule
Credit profile
Vehicle value
A simple way to start is to compare the remaining cost of your current loan with the total cost of the proposed refinance.
For example, if your current loan has a high interest rate and you can refinance to a substantially lower rate without significantly extending the term, the potential savings may be meaningful.
But if the new loan has only a slightly lower rate and includes substantial fees, your actual savings could be small.
This is why you should do the math before signing paperwork.
A refinancing calculator can help you compare different scenarios, but you should always verify the final figures against the actual loan documents.
Final Thoughts
Auto loan refinancing can potentially save money, particularly when your credit has improved or you can qualify for a significantly lower interest rate.
But refinancing is not automatically beneficial.
The most important factor is the overall cost of the new loan.
A lower monthly payment does not necessarily mean a cheaper loan. If the payment falls because the loan term has been extended substantially, you could end up paying more interest and carrying debt on a depreciating vehicle for longer.
A potentially stronger refinancing strategy is to look for a better interest rate while maintaining a similar or shorter repayment period, provided the resulting payment fits comfortably within your budget.
You should also account for origination fees, prepayment penalties, and other costs.
Cash-out refinancing requires additional caution because it increases the amount you owe on the vehicle.
Before refinancing in 2026, compare your current loan with multiple refinancing offers, review your credit, examine the complete fee structure, and calculate the total amount you will pay under each option.
The goal should not simply be to obtain a lower monthly payment.
The goal should be to create a loan that makes sense for your budget while reducing unnecessary interest costs and avoiding an unnecessarily long repayment period.
If the numbers show meaningful savings after all fees and the new terms fit your financial situation, refinancing could be worth considering.