Credit Freeze vs. Credit Lock in 2026: Which Actually Protects Your Identity? (7 Key Differences)
In 2026, identity theft has evolved. With the rise of AI-generated phishing, deepfake verification, and synthetic identity fraud, protecting your financial footprint is no longer optional—it is a necessity. If you are worried about someone opening a credit card or taking out a loan in your name, you have likely come across two primary defenses: the credit freeze and the credit lock.
While both tools restrict access to your credit report to prevent unauthorized new accounts, they are fundamentally different. They differ in their legal backing, their costs, and how they function in the real world. Many consumers end up paying monthly subscription fees for a credit lock when a federally mandated, 100% free credit freeze would provide the exact same foundational protection.
Here is a comprehensive, no-nonsense breakdown of the 7 key differences between a credit freeze and a credit lock, and a step-by-step guide on how to choose the right shield for your financial life.
⚡ Quick Decision Guide: Freeze vs. Lock at a Glance
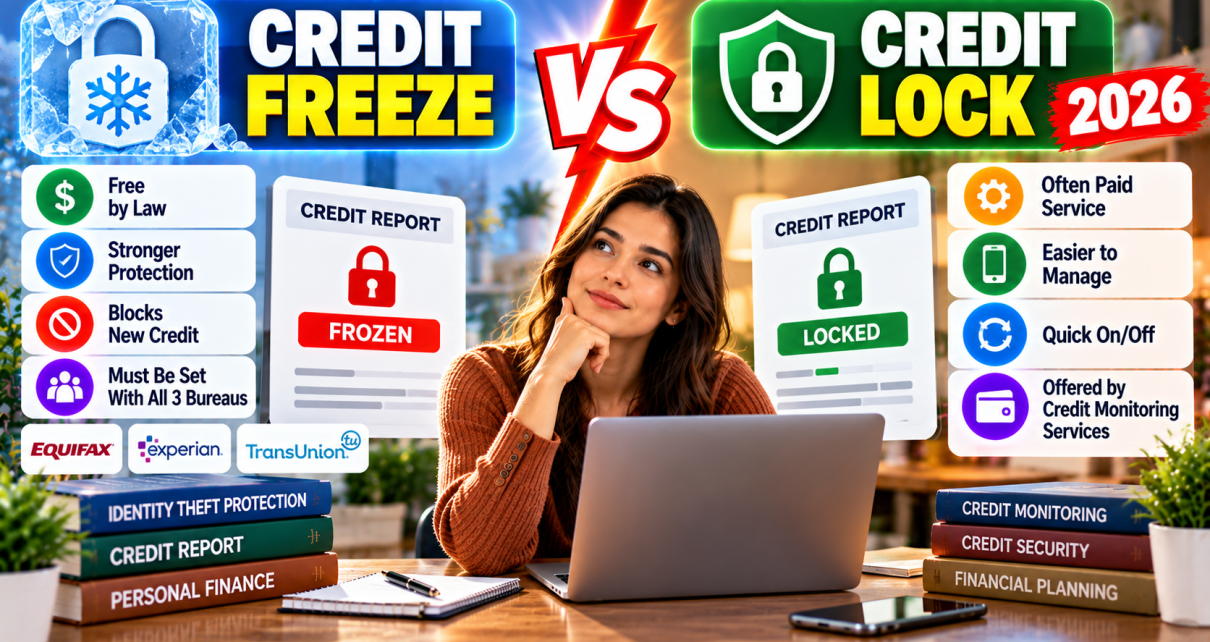
Not sure which one you need? Use this quick reference table to see how they compare in 2026:
|
Feature
|
Credit Freeze (Security Freeze)
|
Credit Lock
|
|---|---|---|
|
Legal Basis
|
Protected under Federal Law (FCRA)
|
Governed by a commercial contract/Terms of Service
|
|
Cost
|
100% Free to place, lift, and remove
|
Often bundled in paid subscriptions ($15–$30/month)
|
|
Management
|
Online bureau portals or phone (PIN required)
|
Mobile apps with intuitive “swipe” or toggle features
|
|
Lift Speed
|
Legally mandated within 1 hour (electronic request)
|
Usually instantaneous via the app
|
|
Best For
|
95% of consumers looking for “set-and-forget” protection
|
Frequent credit applicants (e.g., real estate agents)
|
1. Legal Protection: A Federal Right vs. A Corporate Service
The Credit Freeze: A credit freeze (officially known as a security freeze) is a consumer right established under federal law—specifically, the Economic Growth, Regulatory Relief, and Consumer Protection Act. It legally restricts the three major credit bureaus (Equifax, Experian, and TransUnion) from releasing your credit report to new creditors. Because it is a legal mandate, the bureaus are strictly bound by federal regulations regarding how they handle your freeze.
The Credit Lock: A credit lock is a proprietary product offered by the credit bureaus or third-party financial companies. While it achieves a similar practical result (blocking new credit inquiries), it is governed entirely by the provider’s Terms of Service. If the company changes its app interface, alters its user agreement, or shuts down the service, your lock is subject to those corporate decisions, not federal consumer protection laws.
- The Takeaway: If you want ironclad protection backed by the U.S. government, a security freeze is the superior legal mechanism.
2. Cost: Free by Law vs. Subscription Models
This is the most critical difference for your wallet. Under federal law, placing, temporarily lifting, and permanently removing a security freeze at all three major bureaus is completely free. You do not need to pay a dime, nor do you need to maintain a subscription to keep it active.
Credit locks, however, are rarely standalone free products. They are typically bundled into premium “credit monitoring” or “identity theft protection” memberships, which can cost anywhere from $15 to $40 a month.
- The Takeaway: Do not pay for a subscription simply to get a lock. You can achieve the exact same credit-blocking power for free with a legal freeze.
3. User Experience: Portals vs. Mobile Apps
Historically, the main selling point of a paid credit lock was convenience. Locks were designed with sleek mobile apps that allowed users to “swipe” to lock or unlock their credit in seconds. Freezes used to require calling a phone line or navigating clunky websites.
However, in 2026, the user experience gap has closed. All three major bureaus now offer highly optimized, mobile-friendly online dashboards for managing free security freezes. While you may still need to enter a PIN or log into a secure portal to lift a freeze, the process takes only a few minutes.
- The Takeaway: The convenience gap is no longer wide enough to justify paying a monthly premium for a credit lock.
4. Applying for Credit: The “Thaw” Process
Both tools require you to grant access if you want to apply for a mortgage, auto loan, or new credit card.
- Lifting a Freeze: Federal law requires credit bureaus to lift a freeze within one hour if the request is made electronically or by phone. If you mail the request, it can take up to three business days. You must manage your freeze separately with each bureau (Equifax, Experian, TransUnion). If you know your auto lender only pulls from Experian, you only need to lift the freeze at Experian.
- Unlocking a Lock: Because locks are app-based, unlocking is usually instantaneous.
- The Takeaway: Plan ahead. If you are shopping for a mortgage, temporarily lift your freeze at all three bureaus for a 48-hour window to allow lenders to pull your reports seamlessly.
5. Scope of Protection: What They Actually Stop
A common misconception is that a freeze or lock makes you immune to identity theft. Neither tool protects your existing accounts.
If a thief steals your mail, finds your physical credit card, and goes on a shopping spree, a credit freeze will not stop them. Freezes and locks only prevent the opening of new accounts (like a fraudulent personal loan or a new retail credit card). Furthermore, they do not stop criminals from using your identity to open utility accounts, file fraudulent tax returns, or commit medical identity theft.
- The Takeaway: Think of a freeze as a heavy deadbolt on your front door. It stops intruders from walking in, but it doesn’t stop a burglar who already has a key to your back door (your existing accounts).
6. The “Extras” Trap: Monitoring and Insurance
Credit locks are often bundled with valuable extras, such as dark web monitoring, social security number tracking, and up to $1 million in identity theft insurance.
If you want these features, you do not need to buy a lock to get them. In 2026, you can utilize free credit monitoring tools (like Experian’s free tier, Credit Karma, or your bank’s built-in security features) and purchase a standalone identity theft insurance policy if desired.
- The Takeaway: Evaluate the “extras” separately. Do not pay for a $25/month lock just to get dark web monitoring when free alternatives exist.
7. Long-Term Maintenance: Set-and-Forget vs. Subscription Fatigue
A security freeze is the ultimate “set it and forget it” tool. Once you place it, it remains on your credit file indefinitely until you actively request its removal. You do not need to worry about updating a credit card on file or logging in once a month to prove you are still an active user.
A credit lock relies on an active subscription. If your credit card expires, your payment fails, or you simply forget to renew, your lock will instantly vanish, leaving your credit file wide open to fraudsters without you even realizing it.
- The Takeaway: A free freeze provides permanent peace of mind without the risk of subscription fatigue.
Action Plan: How to Place a Credit Freeze in 2026
If you decide to freeze your credit, you must contact all three bureaus individually. Freezing one does not freeze the others. Here is how to do it:
- Equifax: Create an account on the Equifax Security Freeze portal or call their automated freeze line. You will be issued a PIN to manage future lifts.
- Experian: Log into the Experian Freeze Center online. You can manage your freeze using your Experian login credentials and a PIN.
- TransUnion: Use the TransUnion Credit Freeze portal (formerly TrueIdentity). You can manage your freeze via their website or the TransUnion mobile app.
Pro Tip: Store your freeze PINs in a secure digital password manager (like 1Password or Bitwarden). If you lose them, you will have to go through a lengthy identity verification process to reset them.
What to Do If You Are Already a Victim
If you suspect your identity has already been compromised, a freeze is not enough. You should immediately:
- Place a Fraud Alert: This is free and forces lenders to take extra steps to verify your identity (like calling you directly) before opening a new account. Placing an alert at one bureau automatically triggers it at the other two.
- Check Your Reports: Go to AnnualCreditReport.com to pull your free weekly reports from all three bureaus. Look for unauthorized hard inquiries or accounts.
- Report It: File a report at IdentityTheft.gov to generate an official recovery plan and an Identity Theft Report to send to creditors.
Frequently Asked Questions (FAQ)
Does a credit freeze lower my credit score? No. A freeze has absolutely no impact on your credit score. Your score will continue to calculate normally based on your payment history and credit utilization.
Can I freeze my child’s credit? Yes, and you absolutely should. Children are prime targets for synthetic identity fraud because their clean credit files often go unchecked for years. Under federal law, you can request a free security freeze for any child under the age of 16.
Does a freeze stop my landlord or employer from checking my credit? No. Landlords conducting background/credit checks for rentals, and employers checking credit for specific financial roles, are generally exempt from freeze restrictions. You usually do not need to lift a freeze for these specific inquiries.
Is a credit lock better than a credit freeze? For 95% of consumers, no. A freeze offers the exact same protection for free and is backed by federal law. A lock is only “better” if you are a professional (like a mortgage broker) who applies for credit multiple times a day and values the one-click app convenience over saving money.
Final Thoughts
When deciding between a credit freeze and a credit lock in 2026, the choice usually comes down to cost versus convenience.
For the vast majority of consumers, a free security freeze is the undisputed winner. It provides robust, federally protected, long-term security without the burden of monthly fees or the risk of accidental subscription cancellations. Credit locks still have a niche market for those who demand instant, app-based toggling, but their core function is easily replicated for free.
Protecting your financial identity doesn’t require expensive subscriptions. It requires understanding the tools available to you, using them correctly, and maintaining good digital hygiene.
Disclaimer: This article provides general educational information regarding U.S. consumer credit protections. It does not constitute individualized legal or financial advice. Service features, app interfaces, and procedures can change; always verify current terms directly with the credit bureaus before making financial decisions.