Term Life Insurance vs Whole Life Insurance in 2026: 7 Key Differences to Know
Life insurance can help protect your family financially if you die unexpectedly. However, choosing a policy involves more than comparing death benefits. You also need to consider how long the coverage lasts, how much the premiums cost, and whether the policy offers any value while you are alive.
Two common options in the United States are term life insurance and whole life insurance. Both can provide financial protection for beneficiaries, but they are designed for different needs.
Term life insurance covers a specified period, often 10, 20, or 30 years, depending on the available policy. Whole life insurance is a type of permanent life insurance designed to provide coverage throughout your lifetime, provided the policy remains in force. Whole life policies also generally build cash value.
Neither policy is automatically better. The right choice depends on your financial responsibilities, your budget, your health, and whether you need coverage for a limited period or for life.
Here are seven important differences to understand before buying a policy in 2026.
1. Coverage Duration: A Fixed Term or Lifetime Protection
The most fundamental difference is how long the insurance is designed to last.
Term life insurance provides coverage for a defined number of years. If the insured person dies while the policy is active, the insurer generally pays the death benefit to the beneficiaries, subject to the policy’s terms and conditions.
Consider a 35-year-old parent with a mortgage that has 20 years remaining and two children who still depend on their income. A 20-year term policy might provide protection during the period when the family faces these financial responsibilities.
When the term ends, standard coverage generally ends too. Some policies offer renewal or conversion options, but eligibility, deadlines, costs, and conditions vary.
Whole life insurance is designed to provide lifelong coverage as long as the policy remains in force. This can be useful when a person wants a death benefit that is not limited to a particular stage of life.
For example, someone who wants to leave money to beneficiaries regardless of when they die may consider permanent life insurance. A person who mainly wants to replace income while raising children may have a different reason for purchasing coverage.
What to consider: Identify the financial responsibility you want to protect. If it has a clear end date, term insurance may fit that need. If the need genuinely continues throughout life, permanent coverage may deserve consideration.
2. Premiums: Why Term Life Usually Costs Less
Term life insurance generally costs less than whole life insurance for the same initial death benefit when comparing otherwise similar applicants and coverage terms.
The reason is largely structural. Term insurance covers a limited period and typically does not build cash value. Whole life insurance provides permanent coverage and includes a cash-value component, which contributes to its higher cost.
Actual premiums depend on several factors, including age, health, smoking status, coverage amount, policy design, insurer, and payment terms.
Imagine two applicants are comparing policies with the same $500,000 death benefit. The term policy may offer a substantially lower premium than the whole life policy. However, the exact difference must be established through actual quotes rather than a general rule or an online estimate.
The budget implications matter. Choosing an expensive policy may leave less money for emergency savings, retirement contributions, debt payments, or other family needs.
On the other hand, choosing a policy solely because it is inexpensive can leave a family without adequate protection if the coverage ends too soon.
When comparing quotes, check:
- Whether both policies provide the same initial death benefit.
- How long premiums must be paid.
- Whether premiums are guaranteed to remain level.
- Whether the coverage can expire or change.
- Which benefits and cash values are guaranteed.
A policy is useful only if you can maintain it for as long as your financial plan requires.
3. Cash Value: What Whole Life Insurance Builds
Cash value is one of the main features that distinguishes whole life insurance from standard term life insurance.
Term life insurance generally does not accumulate cash value. Premiums pay for the protection provided during the covered period. If you outlive the term, a standard policy normally does not return the premiums or pay a cash-value benefit.
That does not mean the insurance provided no benefit. The purpose of the policy was to protect against a financial loss during a particular period, whether or not that loss occurred.
Whole life insurance generally accumulates cash value according to the contract. The policy’s financial structure accounts for insurance costs and other expenses, while the cash-value component grows under the policy’s terms.
However, cash value is not the same as a bank savings account.
The amount available if you surrender the policy may be lower than the total premiums paid, especially during the early years. Loans, outstanding interest, surrender charges, and other contractual provisions can also affect the amount you receive.
Before purchasing a whole life policy, request a written illustration showing guaranteed cash values year by year. Review any non-guaranteed projections separately.
What to consider: Do not choose whole life insurance simply because it builds cash value. Compare the total cost, the guaranteed benefits, the surrender value, and the amount of insurance protection you actually need.
4. Flexibility: What Happens When Your Circumstances Change?
Financial needs can change after marriage, the birth of a child, a home purchase, a career change, or a change in household income.
Term life insurance can be appropriate when you want protection for a particular financial period. Some policies also include a conversion option that allows eligible coverage to be converted to permanent insurance within a specified period, sometimes without a new medical examination. The rules depend on the contract.
Conversion may be valuable if your health deteriorates and obtaining a new policy becomes difficult. However, the permanent policy will generally have a higher premium than the original term coverage.
Whole life insurance provides permanent coverage, but changing or ending the contract can have financial consequences. Surrendering the policy means giving up the death benefit in exchange for the applicable surrender value. Borrowing against cash value can reduce the death benefit and may put the policy at risk if the loan is not managed properly.
Before purchasing either policy, ask what options are available if you need to reduce expenses or change your coverage.
Can you renew the policy? Can you convert it? What happens if you stop paying premiums? Can coverage be reduced, and what would that mean for your beneficiaries?
Understanding these details in advance can help prevent an affordable decision today from becoming a difficult financial commitment later.
5. What Happens If You Outlive Your Policy?
Outliving a term life policy is not unusual. In fact, it is what happens when the insured person survives the selected term.
With a standard term policy, the coverage generally expires at the end of the contract period. You do not normally receive a death benefit or a refund simply because you remained alive.
For someone whose mortgage has been paid off and whose children are financially independent, this may be an acceptable outcome. The financial risks the insurance was intended to cover may have decreased.
The situation can be different if you still have dependents or substantial financial responsibilities.
Suppose you purchase a 20-year term policy at age 35. At age 55, the policy ends, but you still support a family member who cannot live independently. You may need additional coverage at a time when your age or health could make new insurance more expensive or difficult to obtain.
Whole life insurance is designed to continue beyond a fixed term, provided the policy remains in force. It may therefore be relevant when a lifelong death benefit is an important objective.
Some term policies offer a return-of-premium feature. These policies generally cost more than comparable standard term policies, and the refund depends on the contract’s requirements. Do not assume every premium will automatically be returned under all circumstances.
Before buying: Consider what your financial obligations may look like when term coverage ends. If you choose permanent insurance, make sure the long-term premium commitment is sustainable.
6. Accessing Cash Value: Loans, Surrender, and Their Costs
Whole life insurance may allow you to access accumulated cash value while you are alive. The available options and their consequences depend on the policy.
One option is a policy loan. You borrow against the policy’s cash value and generally pay interest. An unpaid loan and accumulated interest can reduce the death benefit payable to beneficiaries.
If the outstanding loan becomes too large relative to the policy’s available value, the policy may lapse. Depending on the circumstances and applicable tax rules, a lapse or surrender with outstanding debt can also create tax consequences.
Another option is surrendering the policy. This ends the coverage in exchange for the applicable surrender value, after any relevant deductions. Once the policy is surrendered, the original death benefit is no longer available.
These features should not be treated as free access to savings. Borrowing and surrendering can affect both the policy’s protection and its long-term financial value.
Standard term life insurance generally has no cash value to borrow against.
Before choosing a policy with cash value, ask the insurer to explain the loan interest rate, repayment arrangements, surrender charges, and effect of an outstanding loan on the death benefit.
If you are relying on the cash value for a future financial goal, request written projections and understand which figures are guaranteed.
7. Financial Purpose: Protection or Permanent Planning?
The final difference is how each policy fits into your overall financial plan.
Term life insurance is commonly used to protect dependents against the loss of income during a period when they rely on the insured person financially. The death benefit may help beneficiaries manage living expenses, mortgage payments, education costs, and other obligations.
Whole life insurance may be considered when lifelong coverage is needed or when its cash-value features fit a specific financial objective. In some circumstances, permanent insurance is also used in estate or legacy planning.
However, neither policy replaces a broader financial plan.
A family with substantial life insurance but little emergency savings may still struggle with unexpected expenses. Likewise, a person with an affordable term policy should periodically review whether the coverage amount remains sufficient as debts, income, and family responsibilities change.
Whole life insurance should not automatically be treated as an alternative to investing in stocks, mutual funds, or retirement accounts. Insurance costs, access restrictions, policy guarantees, and individual circumstances all affect its suitability.
If you are considering life insurance for estate planning, tax planning, or another complex financial objective, consult a qualified professional who can evaluate your specific circumstances.
Start with the financial risk you need to protect against. Then compare policies that address that risk at a cost you can maintain.
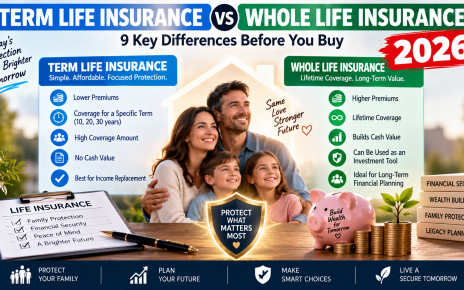
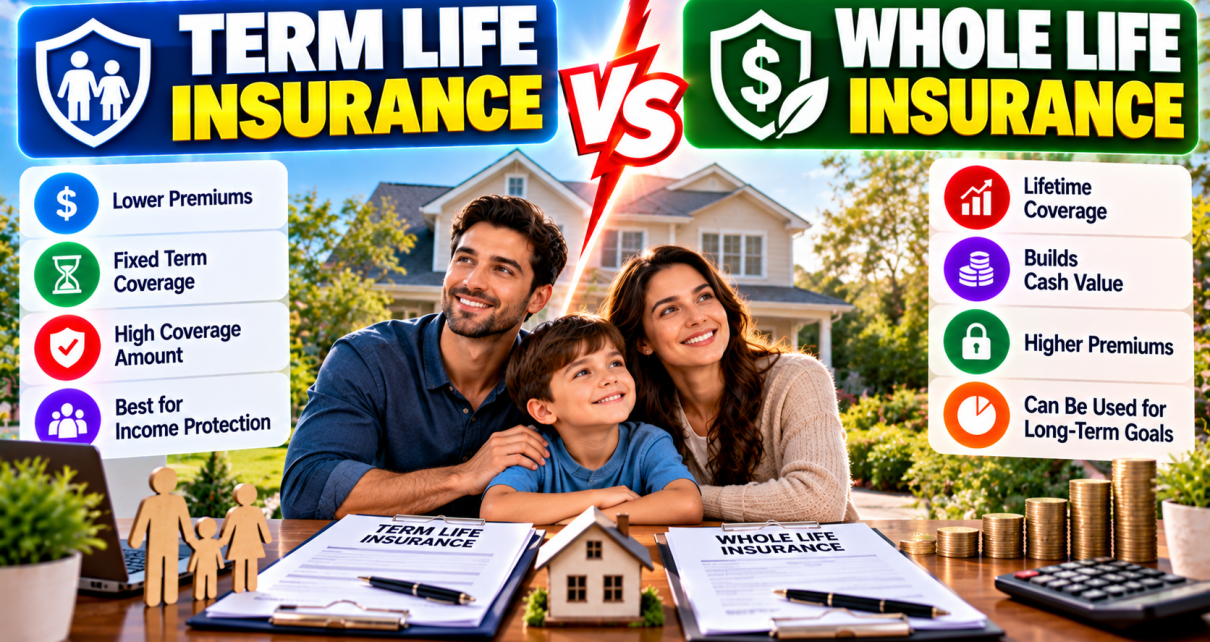
Term Life Insurance vs. Whole Life Insurance: Quick Comparison
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage duration | A specified period | Designed to last for life |
| Typical premium | Usually lower | Usually higher |
| Cash value | Generally none | Generally accumulates |
| End of coverage | Usually expires at the end of the term | Continues if the policy remains in force |
| Policy loans | Generally unavailable | May be available against cash value |
| Renewal or conversion | Depends on the contract | Permanent coverage structure |
| Common purpose | Protecting dependents during a defined period | Lifelong protection and certain long-term planning needs |
Actual benefits, premiums, and options vary by insurer and policy. Compare the contract details rather than relying on the policy name alone.
How to Estimate How Much Life Insurance You Need
Before choosing between term and whole life insurance, estimate the financial support your family would need if you died.
One practical starting point is to consider:
- Income replacement: How much money would your family need to cover essential expenses?
- Outstanding debts: Include mortgage balances and other debts you want the death benefit to help repay.
- Future expenses: Consider education costs, childcare, and support for dependents.
- Existing resources: Account for savings, existing life insurance, and other assets that would be available.
- Time period: Estimate how many years your family may need financial support.
For a simplified example, suppose a household estimates that it would need $50,000 annually for 10 years to replace part of the insured person’s financial contribution. That produces a starting income-replacement estimate of $500,000 before accounting for inflation, investment returns, taxes, existing assets, or changes in spending.
Additional debts and future expenses could increase the amount needed, while savings and existing coverage could reduce it.
This is an illustrative calculation, not a personalized recommendation. A suitable coverage amount depends on the household’s circumstances and should be reviewed as those circumstances change.
Seven Questions to Ask Before Buying
Before signing a life insurance contract, ask the insurer or a licensed insurance professional:
- What death benefit will my beneficiaries receive, and what exclusions or conditions apply?
- How long does the coverage last?
- Are the premiums guaranteed, and how long must I pay them?
- If I buy term insurance, what renewal and conversion options are available?
- If I buy whole life insurance, what are the guaranteed cash values in future years?
- How would a policy loan or surrender affect my coverage and finances?
- Which figures in the policy illustration are guaranteed, and which depend on assumptions?
Request written illustrations and compare similar policies from more than one insurer. Review the contract rather than relying exclusively on a sales presentation.
If you already have life insurance, do not cancel it until replacement coverage has been approved and issued and you have confirmed that the new policy meets your needs. Your health or circumstances may affect your ability to obtain replacement coverage.
Frequently Asked Questions
Is term life insurance better than whole life insurance?
Neither is automatically better. Term life insurance generally provides lower-cost protection for a defined period. Whole life insurance is designed to provide lifelong coverage and accumulate cash value, but it usually costs more. Your financial needs and budget determine which option may be appropriate.
Does whole life insurance always earn a guaranteed return?
Whole life policies generally include contractual guarantees, but the details vary. Guaranteed cash values and death benefits should be distinguished from non-guaranteed dividends or projections. Ask the insurer to explain the guaranteed values in writing.
Can I lose money if I cancel a whole life policy?
Yes. The surrender value may be lower than the premiums paid, particularly during the early years. Applicable charges, policy loans, and other terms can affect the amount received.
What happens when a term life policy expires?
Standard coverage generally ends, and no death benefit is paid merely because the insured person survived the term. Depending on the contract, renewal or conversion options may be available. New coverage may cost more as you age or if your health changes.
Can I have both term and whole life insurance?
Yes. Some people use a combination of policies to address different needs. For example, permanent coverage may address a lifelong objective while term coverage provides additional protection during years of high financial responsibility. The combined premiums should remain affordable, and the arrangement should serve a clear purpose.
Final Thoughts
Term life insurance and whole life insurance serve different purposes. Term life is generally a lower-cost way to protect dependents during a defined period. Whole life insurance is designed to provide lifelong coverage and accumulate cash value, but its higher premiums and contractual conditions require careful consideration.
Before buying in 2026, work out how much financial support your family may need, how long that support might be required, and how much you can comfortably afford to pay. Compare actual policies, guaranteed benefits, coverage exclusions, and the consequences of changing or ending a policy.
The goal is not to buy the policy with the most impressive illustration or the lowest initial premium. It is to choose coverage that addresses a real financial need without creating an unsustainable burden.
Life insurance should help make your family’s financial future more secure. A careful comparison can help you understand the trade-offs before making a long-term commitment.
Editorial note: This article provides general educational information about life insurance in the United States. It is not individualized financial, legal, or tax advice. Policy terms and applicable laws vary, so review the contract and consult a qualified professional when necessary.